预约公益咨询
Book a Complimentary Consultation
健康美丽咨询 → Health & Beauty 财富成长咨询 → Wealth & Growth
或微信扫码直接联系
Or scan to reach us on WeChat
预约公益咨询
Book a Complimentary Consultation
健康美丽咨询 → Health & Beauty 财富成长咨询 → Wealth & Growth
或微信扫码直接联系
Or scan to reach us on WeChat
财富成长 Wealth & Growth › 财富认知讲堂 Wealth Intelligence · 分享此页 →
Wealth Intelligence
这一系列内容,围绕财富认知的建立与提升展开。从底层逻辑出发,逐步理解「做自己的银行」这一核心理念,学习如何借助时间与复利的力量,让财富在长期中以更理性、稳定的方式积累。在这个过程中,我们关注的,不只是财富本身,更是对金钱、选择与人生节奏的重新理解。内容源于实践,沉淀于思考,以清晰而温和的方式呈现,便于反复观看,在日常中逐步建立属于自己的认知与判断力。当认知慢慢清晰,财富将不再只是追逐的目标,而成为可以被理解、被管理、也能够持续积累的结果。由此,个人与家庭的生活品质,也将在不知不觉中稳步提升,让人生拥有更多从容与选择的空间。特别感谢 NS Federation 提供的专业支持。
This series is built around developing and deepening financial awareness. Starting from first principles, it gradually unpacks the core idea of "being your own bank" — learning how to harness time and compounding so that wealth accumulates in a more rational, stable way over the long term. Along the way, what matters is not only wealth itself, but a renewed understanding of money, choice and life's rhythm. The content is drawn from real practice and reflection, presented clearly and gently so it can be watched again and again, helping you steadily build your own awareness and judgement in daily life. As clarity grows, wealth stops being something merely chased — it becomes something understood, managed and sustained. In turn, the quality of life for individuals and families steadily improves, bringing more ease and freedom of choice. Special thanks to NS Federation for their professional support.
财富成长 Wealth & Growth › 财富认知精选 Wealth Wisdom · 分享此页 →
Wealth Wisdom
精选财富认知相关的短句与短文,以精炼的文字启发思考,陪伴日常点滴积累认知。
A curated collection of short quotes and reflections on wealth intelligence — concise words to spark thought and accompany everyday learning.
财富认知 068 · Wealth Wisdom 068一场重大疾病的治疗费用,可能是十年体检费用的几十倍点击查看 ▾The cost of treating a major illness can be dozens of times a decade of check-ups
分享 →一场重大疾病的治疗费用,可能是十年体检费用的几十倍。
The cost of treating a major illness can be dozens of times what a decade of check-ups would cost.
很多人愿意为一次体检、一份保单精打细算,却很少认真算过:真正忽视健康、忽视保障要付出的代价,往往是几十倍、上百倍的账单。世界卫生组织的研究显示,预防性投入与治疗性支出的比例常常是1:8甚至更高——一块钱的提前准备,能省下未来八块钱以上的窟窿。
Many people carefully weigh the cost of a check-up or a policy, yet rarely calculate what neglecting health and protection really costs — often dozens or even hundreds of times more in the end. Research from the World Health Organization shows that the ratio of preventive spending to treatment costs is often 1:8 or higher — a dollar of preparation today can save more than eight dollars of bills tomorrow.
真正的规划,不是等账单来了才后悔,而是提前把这笔账算清楚。
Real planning isn't regretting the bill after it arrives — it's doing the math ahead of time.
财富认知 067 · Wealth Wisdom 067全职照顾家庭,也是需要被保障的价值点击查看 ▾Full-time caregiving is worth protecting too
分享 →全职照顾孩子和家庭的一方,虽然没有工资单,但承担的育儿、家务、协调等工作,换算成市场价值,其实是一笔不小的经济贡献。
The parent who stays home to care for the children and household may not draw a paycheck, but the childcare, housework and coordination they provide represents real economic value if you had to pay someone else to do it.
如果这一方因意外或疾病无法继续承担这些工作,家庭很可能需要额外花钱请人来填补——这笔隐形的价值,同样值得被一份保险覆盖。
If that parent becomes unable to continue due to accident or illness, the family may need to pay someone else to fill the gap. That invisible value deserves to be covered by insurance too.
看不见工资单的付出,一样值得被保护。
Contributions without a paycheck deserve protection just the same.
财富认知 066 · Wealth Wisdom 066只有一份收入的家庭,更需要一份保障点击查看 ▾A one-income family needs protection even more
分享 →如果家里只有一个人在赚钱,这份收入撑起的不只是生活,还有房贷、孩子的教育、父母的养老。
If only one person in the family is earning, that income isn't just supporting daily life — it's carrying the mortgage, the children's education and aging parents too.
一旦这份唯一的收入因为意外或疾病中断,整个家庭的财务结构可能瞬间崩塌。保障规划,就是为这份"唯一"多加一道备份。
If that single income is interrupted by accident or illness, the family's entire financial structure can collapse overnight. Protection planning is what gives that "only" income a backup.
收入来源越单一,保障就越不能少。
The more concentrated your income, the more you can't afford to go without protection.
财富认知 065 · Wealth Wisdom 065一场大病,可能同时打掉收入和存款点击查看 ▾A serious illness can wipe out your income and your savings at once
分享 →癌症、中风、心脏病等重大疾病,治疗费用往往是一笔巨大开支,同时患者也很可能因此无法继续工作。
Major illnesses like cancer, stroke or heart disease often come with enormous treatment costs — and at the same time, the patient is often unable to keep working.
重疾险(Critical Illness Insurance)在确诊后一次性给付一笔现金,可以自由用于治疗、生活开销,或弥补收入的中断,是医疗保险之外的一层重要补充。
Critical illness insurance pays out a lump sum upon diagnosis — money that can be used freely for treatment, living expenses, or replacing lost income. It's an important layer of coverage beyond regular health insurance.
谁能享受这份保障 · Who's Eligible
这类重疾保障,很多时候是以"附加险"的形式加在人寿保单里,不需要额外加保费——美国公民和绿卡持有者大多都可以申请,绿卡通常需要在美持有满2年,才能享受和公民同等的完整产品选择;具体条件因保险公司而异,投保前值得跟专业顾问确认清楚。
This kind of coverage is often added to a life insurance policy as a no-extra-cost rider — both U.S. citizens and green card holders can generally apply, though green card holders typically need at least two years of permanent residency before qualifying for the same full range of products as citizens. Exact requirements vary by insurer, so it's worth confirming the details with a professional advisor before applying.
生病已经很难了,不该再为钱发愁。
Being sick is hard enough — money shouldn't be one more thing to worry about.
财富认知 064 · Wealth Wisdom 064保单贷款,是那间从没被打开过的房间点击查看 ▾The policy loan is the room that's never been opened
分享 →现金价值积累到一定程度后,可以透过保单贷款的方式借出来用——买房首付、抓住投资机会、应对突发开支,都可以不经过银行审核,直接从自己的保单里"借"出来。
Once cash value has built up enough, it can be borrowed against through a policy loan — a down payment, an investment opportunity, an unexpected expense can all be covered by "borrowing" straight from your own policy, with no bank approval required.
跟银行贷款不同,保单贷款不需要信用审核,也没有固定还款期限;虽然保险公司仍会按合同利率计息,但保单里的现金价值不会因为借款而停止增长——你借出去的,是保险公司垫付的钱,你自己的现金价值仍按原来的方式继续计息、继续增长。真正理解这项功能的人不多,但它往往是IUL里被浪费得最多的一间"房间"。
Unlike a bank loan, a policy loan requires no credit check and carries no fixed repayment schedule. Interest still accrues under the policy's terms, but the cash value inside the policy keeps growing as if untouched — what you're borrowing is money the insurer advances against the policy, while your own cash value keeps earning and compounding as usual. Few people fully understand this feature, yet it's often the most under-used "room" in an IUL.
真正被浪费的,不是保费,而是从没打开过的那扇门。
What's truly wasted isn't the premium — it's the door that's never opened.
财富认知 063 · Wealth Wisdom 063买了六个房间的房子,却只住一间点击查看 ▾A six-room house — but most people only ever live in one
分享 →很多人买了IUL(指数型万能寿险),却只把它当成一份身故保障——就像买了一栋六个房间的房子,却只住其中一间。
Many people buy an IUL (Indexed Universal Life) and treat it as nothing more than a death benefit — like buying a six-room house and only ever living in one room of it.
IUL其实至少有三重功能:身故保障、现金价值的延税储蓄增长,以及随时可以借出来用的保单贷款——就像一部智能手机除了打电话,还能拍照、导航、处理工作,但很多人买了智能手机,却只用来打电话。
An IUL actually comes with at least three built-in functions: a death benefit, tax-deferred cash-value growth, and a policy loan you can draw on whenever you need it — much like a smartphone that can also take photos, navigate, and handle work, yet plenty of people buy one and only ever use it to make calls.
工具本身没有被浪费,浪费的是从没打开过的那几间房。
The tool itself isn't wasted — what's wasted are the rooms that never get opened.
财富认知 062 · Wealth Wisdom 062退休后的税级,其实可以提前规划点击查看 ▾Your tax bracket in retirement can actually be planned ahead of time
分享 →很多人以为退休后收入变少,税自然就少了,但如果退休金主要来自401(k)、传统IRA等税延账户,提领时全部算作应税收入,税级可能比想象中更高。
Many people assume that once retired, lower income automatically means lower taxes. But if retirement income comes mainly from tax-deferred accounts like a 401(k) or traditional IRA, withdrawals count as fully taxable income — and the bracket can end up higher than expected.
透过提前配置不同税务属性的账户(应税、税延、免税),退休后可以根据当年需要灵活选择提领来源,把整体税负控制在更低的区间。
By structuring accounts with different tax treatments ahead of time — taxable, tax-deferred and tax-free — retirees can flexibly choose where to withdraw from each year, keeping their overall tax burden in a lower range.
退休规划的关键,不是赚多少,而是能留下多少。
The key to retirement planning isn't how much you earn — it's how much you get to keep.
财富认知 061 · Wealth Wisdom 061固定指数年金,给退休收入设一个"保底线"点击查看 ▾A fixed index annuity puts a floor under retirement income
分享 →固定指数年金(Fixed Index Annuity)由保险公司发行,收益与市场指数挂钩,但设有0%保底——市场下跌时账户价值不受影响,是退休规划里风险相对可控的一类工具。
A fixed index annuity is issued by an insurance company, with returns tied to a market index but protected by a 0% floor — account value isn't affected when the market falls, making it a comparatively risk-controlled tool in retirement planning.
更重要的是,很多年金产品可以搭配"终身收入权益",把一笔本金转换为终身按月发放的现金流——不管活多久,这笔钱都不会断,是应对"长寿风险"最直接的工具之一。
More importantly, many annuity products can be paired with a lifetime income rider, converting a lump sum into a monthly cash flow for life — no matter how long you live, the payments don't stop, making it one of the most direct tools for addressing longevity risk.
与银行CD相比 · vs. Bank CDs
同样追求"本金安全",固定指数年金与银行CD的差别主要在三处。收益上,CD利率通常在3%~5%区间且每年固定,而指数年金收益挂钩市场表现,历史平均年化多在4%~6%;税务上,CD利息无论是否提取,每年都要计入当年应税收入,年金则在提取前一直享受税递延增长,同样的复利速度下能滚存出更多实际收益。流动性方面,CD到期前提前支取通常要扣3~12个月利息作为罚金,而多数年金合约允许每年免罚金提取最多10%的账户价值。CD受FDIC直接保险,年金则依托保险公司自身的财务实力与各州保障协会的保底额度——安全性的来源不同,但都不是"赌市场"的工具。真正的分界线在于:CD到期即结束,年金却可以选择转换成终身收入,覆盖CD解决不了的"活得比钱久"的问题。
Both aim for principal safety, but a fixed index annuity differs from a bank CD in three key ways. On returns, CD rates typically sit around 3%–5% and stay fixed, while index annuity returns are tied to market performance, historically averaging 4%–6% annually. On taxes, CD interest is taxed as income every year whether or not you withdraw it, while annuity growth is tax-deferred until withdrawal — at the same compounding rate, the annuity retains more real return. On liquidity, withdrawing from a CD before maturity usually costs 3–12 months of interest in penalties, while most annuity contracts allow up to 10% of account value to be withdrawn penalty-free each year. CDs carry direct FDIC insurance; annuities rely on the issuing insurer's own financial strength plus state guaranty association backstops — different sources of safety, but neither is a bet on the market. The real dividing line: a CD simply ends at maturity, while an annuity can convert into lifetime income, addressing the "outliving your money" problem a CD can't.
保底不是不想要收益,是不想在市场最差的时候被迫卖出。
A floor isn't about giving up on returns — it's about not being forced to sell when the market is at its worst.
财富认知 060 · Wealth Wisdom 060IUL 的现金价值,增长和提领都能免税点击查看 ▾An IUL's cash value can grow and be withdrawn tax-free
分享 →IUL(指数型万能寿险)的现金价值跟随指数表现增长,设有0%保底,市场下跌时本金不受损。
An IUL's (Indexed Universal Life) cash value grows in step with a market index, with a 0% floor — your principal isn't touched when the market falls.
更关键的是,现金价值的增长是延税的,透过保单贷款的方式提领,通常也不产生应税收入——是少数能同时做到"增长"与"免税提领"的金融工具。
More importantly, that growth is tax-deferred, and withdrawing it through a policy loan typically doesn't create taxable income — making it one of the rare tools that combines growth with tax-free access.
延税增长,是什么意思 · What "Tax-Deferred" Actually Means
"延税"和"免税"是两回事,容易被混为一谈。现金价值在保单内的增长属于延税——账户里的收益不会像股票分红、银行利息那样每年被计入应税收入,可以不受税务拖慢地持续复利滚存;但如果以"提取"(withdrawal)的方式直接拿出超过已交保费的部分,这部分收益依然要交税。真正把这笔钱变成免税的,是提领的方式——透过保单贷款(policy loan)而不是提取来用钱。保单贷款在税法上被认定为"借款"而非"收入",只要保单持续有效、未被归类为修正性保单(MEC),这笔贷款就不产生应税所得,通常也没有固定还款期限,多数情况下在身故时用理赔金自动冲抵。
"Tax-deferred" and "tax-free" are two different things, and they're easy to conflate. Cash value growth inside the policy is tax-deferred — unlike stock dividends or bank interest, it isn't counted as taxable income each year, so it can keep compounding without being slowed by taxes. But if you take money out as a direct withdrawal beyond what you've paid in premiums, that gain is still taxable. What actually makes the money tax-free is how you access it — through a policy loan rather than a withdrawal. Under tax law, a policy loan is treated as debt, not income; as long as the policy stays in force and isn't classified as a Modified Endowment Contract (MEC), the loan creates no taxable income, typically carries no fixed repayment schedule, and is usually offset automatically by the death benefit when the insured passes.
免税资产的意义 · The Point of Holding Tax-Free Assets
这类工具的价值不只在"省一次税",更在于给退休资产配置多加一个"免税桶"。多数人的退休资产集中在401(k)、传统IRA这类"延税桶"——存的时候免税,但取的时候要按提领当年的税率全额纳税;如果退休后税率不降反升,实际能用的钱可能比预期少。手上握有一部分真正免税的资产(Roth IRA、市政债券,或IUL现金价值),意味着退休后可以根据当年身处的税级,灵活决定从哪个"桶"取钱,把整体税务负担摊薄、变得可控。这才是"利用免税资产"的真正意义:不是完全避税,而是把主动权握在自己手里。
The value of this kind of tool isn't just saving tax once — it's adding a "tax-free bucket" to your retirement asset mix. Most people's retirement savings sit in tax-deferred buckets like a 401(k) or traditional IRA — tax-free going in, but fully taxed at whatever rate applies the year you withdraw. If tax rates rise rather than fall by the time you retire, you may end up with less usable income than expected. Holding some genuinely tax-free assets — a Roth IRA, municipal bonds, or IUL cash value — means you can choose which bucket to draw from each year based on your tax bracket at the time, spreading out and controlling your overall tax burden. That's the real point of holding tax-free assets: not avoiding tax altogether, but keeping the choice in your own hands.
会赚钱是本事,会免税是智慧。
Earning money is a skill — earning it tax-free is wisdom.
财富认知 059 · Wealth Wisdom 059一份人寿保险,需要时能立刻变成现金点击查看 ▾A life insurance policy can turn into cash the moment it's needed
分享 →遗产认证程序(Probate)往往需要数月甚至数年才能完成,期间家人可能连生活费、丧葬费都周转不开。
The probate process can take months, sometimes years, to complete — and during that time, family members may not even be able to cover living expenses or funeral costs.
人寿保险理赔通常几周内就能到账,而且不需要经过遗产认证程序,是留给家人最快速、最直接的一笔现金——用来应对眼前的开销,争取处理遗产的从容时间。
A life insurance payout typically arrives within weeks, and it bypasses probate entirely — making it the fastest, most direct cash a family can receive, covering immediate needs while giving them time to handle the rest of the estate calmly.
真正的保障,是在最需要的时候,钱能马上到位。
Real protection means the money is there the moment it's needed most.
财富认知 058 · Wealth Wisdom 05870% 的家族财富,会在第二代手中消失点击查看 ▾70% of family wealth disappears by the second generation
分享 →美国的研究显示,大约70%的家族财富会在第二代手中消失,90%会在第三代之前彻底流失。
U.S. studies show that roughly 70% of family wealth disappears by the second generation, and 90% is gone by the third.
造成这个结果的,往往不是投资失误,而是缺乏沟通、缺乏规划、缺乏对下一代的财商教育。传承规划,从来不只是法律文件,更是一场跨代的对话。
The cause is rarely bad investments — it's usually a lack of communication, a lack of planning, and a lack of financial education passed to the next generation. Legacy planning was never just legal paperwork — it's a conversation across generations.
提前规划,才能打破"富不过三代"的魔咒。
Planning ahead is how you break the "wealth never survives three generations" curse.
财富认知 057 · Wealth Wisdom 057留给孩子最好的,不只是钱,是价值观点击查看 ▾The best thing to leave your children isn't just money — it's values
分享 →很多白手起家的第一代,最担心的不是留不下钱,而是留下的钱被下一代挥霍。
For many self-made first-generation wealth builders, the real fear isn't leaving too little money — it's the next generation squandering what's left.
透过信托设置分阶段的分配条款(比如按年龄、按教育、按创业里程碑发放),能让财富的传承同时伴随责任感的传承,而不是一次性给完就结束。
Structuring a trust with staged distribution terms — tied to age, education, or entrepreneurial milestones — lets wealth transfer alongside a sense of responsibility, instead of ending the moment it's all handed over.
真正的富过三代,靠的是规划,不是运气。
Wealth that truly lasts three generations comes from planning, not luck.
财富认知 056 · Wealth Wisdom 056没有规划的遗产,最容易变成家庭的裂痕点击查看 ▾An unplanned inheritance is often what splits a family apart
分享 →很多家庭的矛盾,不是发生在父母在世的时候,而是在遗产分配的那一刻爆发。
In many families, the real conflict doesn't happen while the parents are alive — it erupts the moment the inheritance is divided.
没有清楚的遗嘱或信托安排,子女之间很容易因为"谁分得多、谁分得少"产生猜忌,甚至对簿公堂。提前把规划和沟通做清楚,才是对家庭关系最好的保护。
Without a clear will or trust, siblings can easily grow suspicious of who got more or less — sometimes ending up in court. Sorting out the planning and the conversation ahead of time is the best protection for family relationships.
遗产也可能是税务负担 · Inheritance Can Also Be a Tax Burden
多数家庭其实不用担心联邦遗产税——2026年的免税额已提高到每人1,500万美元(夫妻合计3,000万),绝大部分资产传承根本碰不到这条线。但一个常被忽略的真相是:401(k)、传统IRA这类退休账户,子女继承后仍要按SECURE法案的"10年规则",在10年内把账户全部提领完毕,每一笔提领都要计入当年应税收入。如果父母一辈子省吃俭用攒下几百万退休金,子女却恰好在自己收入高峰期,被迫十年内集中提领、推高到更高税级——辛苦攒下的财富,反而变成了下一代的一笔税单。这也是遗嘱和信托选择上真正的认知门槛:选对工具、提前规划,才能让"赚得多"变成一份礼物,而不是留给下一代的负担。
Most families don't actually need to worry about federal estate tax — the 2026 exemption has risen to $15 million per person ($30 million per married couple), well beyond what most estates ever reach. But an often-overlooked truth: retirement accounts like a 401(k) or traditional IRA still trigger the SECURE Act's "10-year rule" for heirs — the entire account must be emptied within 10 years of inheriting it, and every withdrawal counts as taxable income that year. If parents spent a lifetime building up a substantial nest egg, their children could be forced to withdraw it all during their own peak earning years, pushed into a higher tax bracket in the process — turning hard-earned wealth into a tax bill for the next generation. This is the real cognitive threshold behind choosing a will or trust: pick the right tool and plan ahead, and "earning more" becomes a gift instead of a burden left to the next generation.
最好的传承,是没有争议的传承。
The best legacy is one that leaves nothing to fight over.
财富认知 055 · Wealth Wisdom 055婚前的一份规划,是对婚姻最大的尊重点击查看 ▾Planning before marriage is the greatest respect you can show it
分享 →谈婚前协议(Prenup)常常让人觉得"不浪漫",甚至联想到不信任。
Bringing up a prenup often feels "unromantic" — even like a sign of distrust.
但真正成熟的规划,是把丑话说在前面,把各自婚前的资产、家族企业、未来的继承清楚划分,反而能让婚姻少一些因为财务而起的猜忌与争执。
But truly mature planning means having the hard conversation up front — clearly separating premarital assets, family businesses and future inheritances — which actually leaves less room for money-driven suspicion and conflict in the marriage.
把财务讲清楚,才能把感情谈长久。
Getting the finances clear is what lets the relationship last.
财富认知 054 · Wealth Wisdom 054房产投资越多,越需要懂得隔离风险点击查看 ▾The more real estate you own, the more you need to isolate the risk
分享 →房东最常见的风险,来自租客的意外受伤或财产纠纷——一旦被起诉,个人名下的其他资产也可能受到牵连。
A landlord's most common risk comes from a tenant's accidental injury or property dispute — and once sued, other assets under your own name can be pulled in too.
把每一套出租房产放进独立的LLC,是美国房产投资者最常用的隔离风险方式之一——一套房产出事,不会连累到其他资产。
Placing each rental property in its own separate LLC is one of the most common risk-isolation strategies U.S. real estate investors use — trouble with one property won't drag down the rest of your assets.
投资越做越大,风险管理也要跟着升级。
As your portfolio grows, your risk management needs to grow with it.
财富认知 053 · Wealth Wisdom 053专业人士最怕的,不是没生意,而是一次诉讼点击查看 ▾What professionals fear most isn't a slow year — it's a single lawsuit
分享 →医生、律师、地产经纪等专业人士,收入往往不低,但也常常暴露在职业责任风险中。
Doctors, lawyers, real estate agents and other professionals often earn well — but they're also frequently exposed to professional liability risk.
一次医疗纠纷或专业过失诉讼,可能让多年积累的资产在一夜之间受到威胁。透过信托、保险与法律架构做好资产隔离,才能让专业风险不波及家庭生活。
A single malpractice claim or professional negligence lawsuit can put years of accumulated assets at risk overnight. Using trusts, insurance and legal structures to isolate assets keeps professional risk from spilling into family life.
专业能力保护事业,资产隔离保护家人。
Professional skill protects your career — asset protection protects your family.
财富认知 052 · Wealth Wisdom 052创业者的第一课,是把公司和家庭分开点击查看 ▾A business owner's first lesson: separate the company from the family
分享 →很多第一次创业的人,把个人存款和公司账户混着用,觉得反正都是自己的钱。
Many first-time business owners mix personal savings with company accounts, figuring it's all their own money anyway.
但一旦公司遇到诉讼或债务问题,没有做好法律架构隔离(如LLC),个人和家庭资产也可能被牵连进去。
But once the company faces a lawsuit or debt issue, without proper legal separation — like an LLC — personal and family assets can get pulled in too.
分清楚"公司的钱"和"家人的钱",是每个创业者都该补的第一课。
Clearly separating "the company's money" from "the family's money" is a lesson every entrepreneur needs to learn early.
财富认知 051 · Wealth Wisdom 051教育基金和退休金,从来不是二选一点击查看 ▾Education savings and retirement savings were never an either-or
分享 →很多父母把孩子的教育放在第一位,宁愿牺牲自己的退休规划,也要先顾孩子的学费。
Many parents put their children's education first, willing to sacrifice their own retirement planning just to cover tuition.
但现实是:孩子可以贷款读大学,父母的退休却没有"贷款"这个选项。真正稳妥的规划,是两者同时进行,而不是牺牲一个成全另一个。
But the reality is: children can take out loans for college — parents don't have a "loan" option for retirement. True, sound planning means doing both at once, not sacrificing one for the other.
照顾好自己的晚年,本身也是给孩子最大的礼物。
Taking care of your own retirement is, in itself, one of the greatest gifts you can give your children.
财富认知 050 · Wealth Wisdom 050祖父母的一份心意,也能变成孙辈的教育基金点击查看 ▾A grandparent's gift can become a grandchild's education fund
分享 →逢年过节给孙辈的红包,很多时候花完就花完了;但如果把这份心意存进529账户,就能陪着孩子一路成长,变成实实在在的教育基金。
The money grandparents give grandchildren for holidays often just gets spent and forgotten. But putting that same gift into a 529 account lets it grow alongside the child, becoming a real education fund.
祖父母出资的529账户,还能同时享有一定的赠与税优惠;而且自2024年助学金规则简化后,祖父母名下的529账户已经不再计入孩子申请助学金时的资产审核——是隔代传承心意与财富的双重方式。
A 529 account funded by grandparents can also come with certain gift-tax advantages — and since the 2024 FAFSA simplification, grandparent-owned 529 accounts no longer count against a grandchild's financial aid eligibility. It's a way to pass down both love and wealth across generations at once.
529并非唯一或最优解 · Why a 529 Isn't Always the Best Choice
但529也有局限,值得提前想清楚。它主要为教育支出设计,如果孩子最终没有走大学这条路、或是拿到奖学金后资金有剩余,非合格提领的收益部分要缴所得税外加10%罚金——2026年起虽然多了一条出路,闲置资金可以一次性转入孩子自己的Roth IRA,但终身上限只有3.5万美元,且账户需存续满15年等条件,操作空间有限。另外,如果账户是由父母本人(而非祖父母)持有,申请助学金时,账户价值最多有5.64%会被计入家庭可动用资产,可能拉低孩子拿到的助学金额度。相比之下,具备现金价值的人寿保单不受"必须用于教育"的限制,取用方式更灵活,通常也不计入助学金资产评估——对希望兼顾教育金和不确定性的家庭,是值得考虑的补充选项,而不是"529或什么都没有"的二选一。
But a 529 has its limits, worth thinking through in advance. It's designed primarily for education expenses — if a child doesn't end up going to college, or ends up with leftover funds after a scholarship, the earnings portion of a non-qualified withdrawal is subject to income tax plus a 10% penalty. Starting in 2026 there's one more outlet — unused funds can be rolled into the child's own Roth IRA — but the lifetime cap is only $35,000, and the account must have been open at least 15 years, among other conditions, so the room to maneuver is limited. Also, if the account is owned by a parent rather than a grandparent, up to 5.64% of its value counts toward the family's assets when calculating financial aid, which can reduce the aid a child receives. By contrast, a life insurance policy with cash value isn't restricted to "must be used for education," offers more flexible access, and typically isn't counted in financial-aid asset calculations at all — worth considering as a complement for families who want to hedge for education and uncertainty at once, rather than treating it as a strict either-or with a 529.
最好的礼物,是能陪孩子走得更远的那一份。
The best gift is the one that helps a child go further.
财富认知 049 · Wealth Wisdom 049529 计划,不只是为了大学点击查看 ▾A 529 plan isn't just for college
分享 →很多人以为529账户只能用来交大学学费,其实它也能用于K-12私立学校学费、学徒项目,甚至部分学生贷款的偿还。
Many people think a 529 account can only be used for college tuition — but it can also cover K-12 private school tuition, apprenticeship programs, and even some student loan repayment.
受益人也可以更换——如果一个孩子用不完,可以转给兄弟姐妹,甚至转给未来的孙辈,账户不会因为一个孩子不上大学就浪费掉。
The beneficiary can also be changed — if one child doesn't use it all, it can be transferred to a sibling, or even a future grandchild. The account isn't wasted just because one child doesn't attend college.
IUL 教育规划,比529好在哪里 · Where an IUL Beats a 529 for Education Planning
作为529的补充甚至替代,一些家庭会用IUL(指数型万能寿险)的现金价值做教育规划,优势主要在四点。第一,用途完全不受限——529资金若不用于合规教育支出,收益部分要缴所得税加10%罚金;IUL现金价值不论未来是用于学费、创业、买房还是别的人生阶段,都没有"必须是教育用途"这道门槛。第二,通常不计入大学助学金资产评估——529若由父母持有,账户价值最多有5.64%会拉低孩子的助学金额度,而人寿保单的现金价值一般不在FAFSA的资产审核范围内。第三,避开"入学恰好撞上市场下跌"的时点风险——529资金多是市场投资,如果孩子18岁那年正好遇上熊市,要么被迫割肉提取、要么延后入学;IUL现金价值设有0%保底,不会因市场下跌而缩水。第四,多一层保障——如果出资的父母中途身故,IUL的身故保险金能确保孩子的教育资金依然到位,这是529完全没有的功能。当然,IUL的费用结构和保单设计比529复杂,需要专业规划配置得当,不是简单地"存钱"。
As a complement to — or even an alternative for — a 529, some families use an IUL's (Indexed Universal Life) cash value for education planning, mainly for four reasons. First, the money has no usage restriction at all — 529 earnings withdrawn for non-qualified expenses are hit with income tax plus a 10% penalty, while IUL cash value can go toward tuition, a business, a house, or any other life stage with no "must be for education" requirement. Second, it typically isn't counted when college financial aid is assessed — a parent-owned 529 can count up to 5.64% of its value against a child's aid eligibility, while cash-value life insurance generally falls outside FAFSA's asset review. Third, it sidesteps the risk of college start coinciding with a market downturn — 529 funds are mostly market-invested, so if a bear market hits the year a child turns 18, the family either sells at a loss or delays enrollment; IUL cash value carries a 0% floor and won't shrink when markets fall. Fourth, it adds a layer of protection — if the funding parent passes away partway through, the IUL's death benefit ensures the child's education fund is still there, something a 529 simply can't offer. That said, an IUL's fee structure and policy design are more complex than a 529's and need proper professional planning — it isn't as simple as just saving money.
了解清楚工具的灵活性,才能把每一分钱都用在刀刃上。
Understanding how flexible the tool really is means every dollar gets put to good use.
财富认知 048 · Wealth Wisdom 048学费在涨,规划要趁早点击查看 ▾Tuition keeps rising — plan while you still have time
分享 →美国大学学费几乎每年都在上涨,私立大学一年学费加食宿,很多家庭已经要接近7-8万美元。
U.S. college tuition rises almost every year — at private universities, tuition plus room and board can already run close to $70,000–$80,000 a year for many families.
如果没有提前规划,等孩子真正上大学时,压力会一次性压过来;透过529计划分年投入,能把这份压力拆解到十几年里慢慢消化。
Without planning ahead, that pressure lands all at once when your child actually starts college. Contributing to a 529 plan year by year spreads that pressure out over a decade or more instead.
AI时代,教育规划的另一重挑战 · Education Planning's New Wildcard: AI
这几年,"大学到底值不值得读、该读什么专业"变得比以前更难回答——AI正在快速改变各行各业需要的技能,一些曾经热门的专业,未来的就业前景已经不再像过去那样确定。这也是为什么教育资金规划,除了"存够钱",更要考虑"存的钱够不够灵活":如果孩子未来选的不是传统四年制大学,而是职业培训、编程训练营、创业,或者中途转换方向,手上的资金能不能跟着调整,同样重要。这也是为什么越来越多家庭,在529之外同时配置更灵活的教育资金工具(详见049、050)——不是不相信教育的价值,而是不想把所有筹码,都押在一条尚未确定的路径上。
In recent years, "is college even worth it, and what should you study" has become a harder question to answer — AI is rapidly reshaping the skills every industry needs, and career prospects for some once-reliable majors are no longer as certain as they used to be. That's why education funding isn't just about saving enough — it's also about saving in a way that stays flexible. If a child ends up choosing vocational training, a coding bootcamp, starting a business, or switching direction midway instead of a traditional four-year degree, whether your funds can adapt matters just as much. That's also why more families are pairing a 529 with more flexible education-funding tools (see #049 and #050) — not because they doubt the value of education, but because they don't want to bet everything on one path that isn't guaranteed anymore.
教育规划不是一次性的决定,而是一场十几年的马拉松。
Education planning isn't a one-time decision — it's a marathon that spans over a decade.
财富认知 047 · Wealth Wisdom 047保障不是花钱,而是把爱变成承诺点击查看 ▾Protection isn't an expense — it's love turned into a promise
分享 →家人愿意为彼此付出一切,但风险从不会提前打招呼。
Family will give everything for one another, but risk never calls ahead to warn you.
在美国,家庭保障规划通常从一份合适的人寿保险开始——在意外和疾病来临之前,先为家人筑起一道防线。
In the U.S., family protection planning usually starts with the right life insurance policy — building a line of defense for your family before accident or illness ever arrives.
保障不是花钱,而是把爱变成一份实实在在的承诺。
Protection isn't an expense — it's love turned into a real, tangible promise.
财富认知 046 · Wealth Wisdom 046省下的税,就是多赚的钱点击查看 ▾The tax you save is money you earned twice
分享 →多数人只关心今天赚多少,却很少想过,未来要为这些钱交多少税。
Most people only focus on how much they earn today, rarely thinking about how much tax that money will owe in the future.
在美国,合理配置 Roth IRA、人寿保险现金价值等免税资产,能让你在退休提领时,少一份税务负担,多一份实际到手的现金流。
In the U.S., properly structuring tax-advantaged assets like a Roth IRA or life insurance cash value means less tax burden when you withdraw in retirement, and more cash flow that's actually yours to keep.
省下的税,就是多赚的钱。
The tax you save is money you earned twice.
财富认知 045 · Wealth Wisdom 045财富传承,传的不只是钱点击查看 ▾Legacy planning passes down more than just money
分享 →没有规划的财富传承,往往在下一代手中,变成争产的开始,而不是延续的开始。
Wealth passed down without a plan often becomes the start of a family dispute for the next generation, not a continuation of what was built.
合理的美国遗产规划(如设立信托),能让财富平稳过渡给下一代,避免遗产认证程序(Probate)的拖延与损耗,也让爱与责任一并传递下去。
Proper U.S. estate planning — such as setting up a trust — lets wealth transfer smoothly to the next generation, avoids the delays and costs of probate, and passes down love and responsibility along with it.
真正的传承,是把智慧和保障一起留给下一代。
True legacy is leaving the next generation both wisdom and protection.
财富认知 044 · Wealth Wisdom 044真正的富有,不只是拥有,更是懂得保护点击查看 ▾True wealth isn't just what you have — it's knowing how to protect it
分享 →很多人努力一辈子积累的资产,却可能因为一次官司、一次债务纠纷,一夜之间受到冲击。
Many people spend a lifetime building their assets, only to see them threatened overnight by a single lawsuit or debt dispute.
在美国,透过 LLC、信托等法律架构做资产隔离规划,就是把个人资产和经营风险分开管理——生意上的风险,不该牵连到家人的生活。
In the U.S., using legal structures like LLCs and trusts for asset protection means separating personal assets from business risk — a risk in your business shouldn't put your family's life on the line.
真正的富有,不只是拥有多少,更是懂得如何保护它。
True wealth isn't just what you have — it's knowing how to protect it.
财富认知 043 · Wealth Wisdom 043教育规划,是给孩子最早的一份礼物点击查看 ▾Education planning is the earliest gift you can give your child
分享 →孩子的教育,从来不是等到需要时才开始准备的。
A child's education was never something to start preparing for only once the bills arrive.
美国的 529 教育储蓄计划,是许多家庭最常用的教育基金工具——成长部分免税,用于教育支出时提取也免税,越早开始,复利的时间就越长。
The U.S. 529 education savings plan is one of the tools families use most — growth is tax-free, and withdrawals for education expenses are tax-free too. The earlier you start, the longer compounding has to work.
今天存下的一点点,会变成孩子未来更多的选择权。
What you set aside today becomes more choices for your child tomorrow.
财富认知 033 · Wealth Wisdom 033最大的财富不是存款点击查看 ▾The greatest wealth isn't your savings
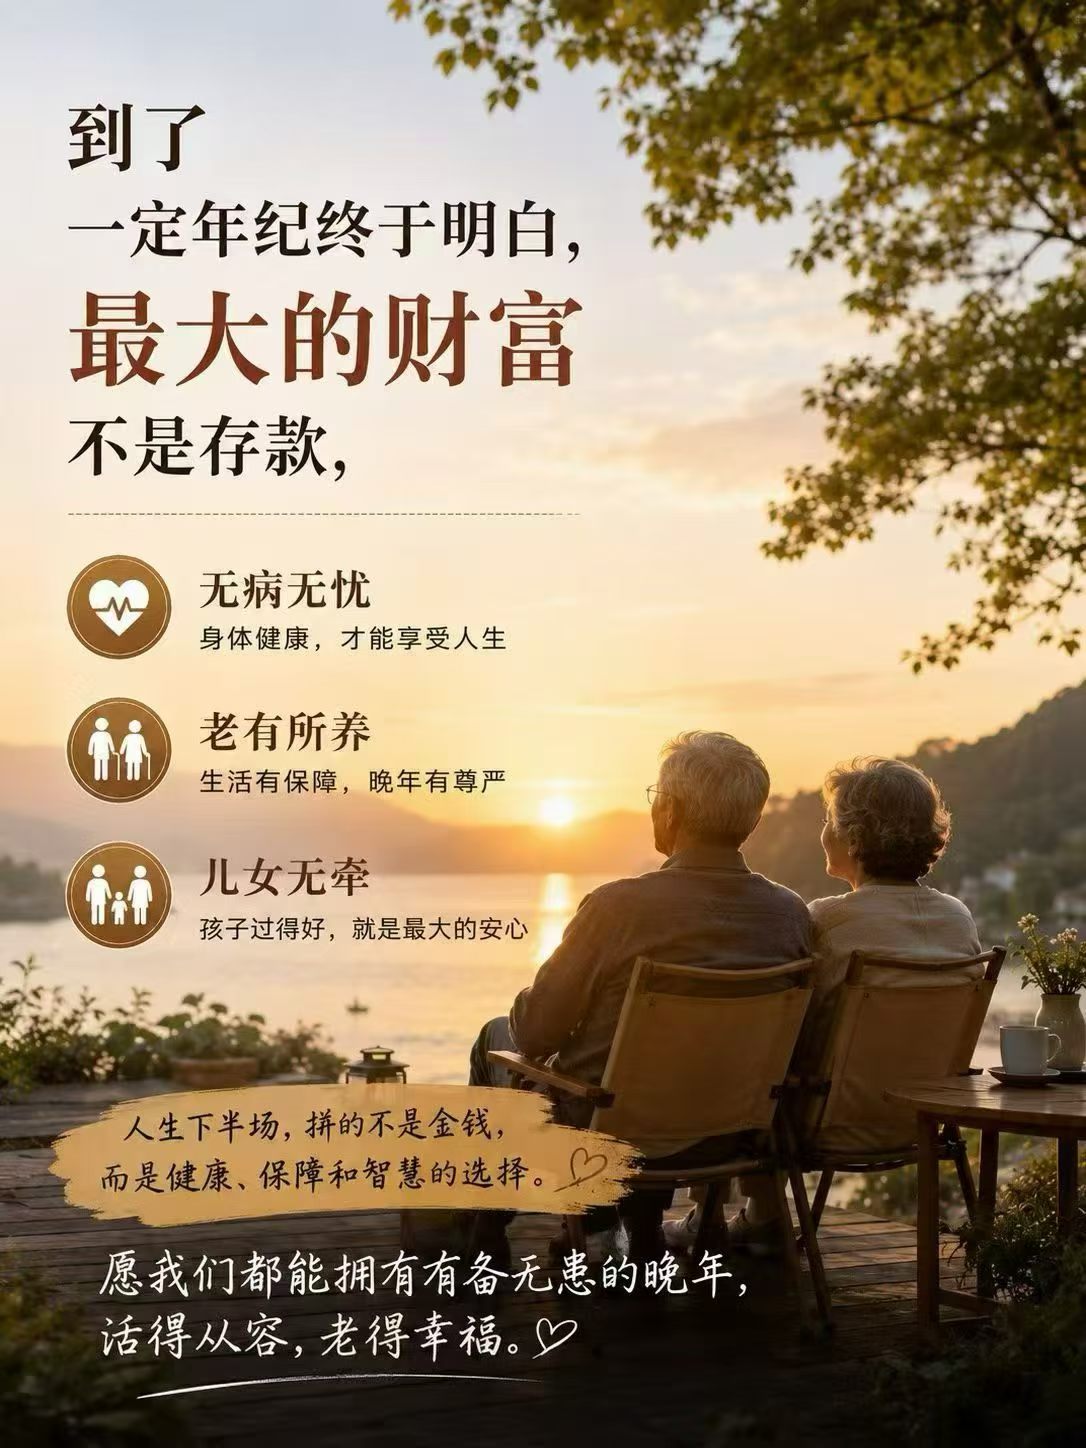
分享 →到了一定年纪终于明白,最大的财富不是存款。
At a certain age, you finally understand — the greatest wealth isn't your savings.
无病无忧——身体健康,才能享受人生;老有所养——生活有保障,晚年有尊严;儿女无牵——孩子过得好,就是最大的安心。
Free from illness and worry — only good health lets you truly enjoy life. Cared for in old age — a secure life means a dignified retirement. Children unburdened — knowing your kids are doing well is the greatest peace of mind.
人生下半场,拼的不是金钱,而是健康、保障和智慧的选择。
In the second half of life, what matters isn't money — it's health, protection, and wise choices.
愿我们都能拥有有备无患的晚年,活得从容,老得幸福。
May we all have a well-prepared old age — living with ease, growing old with happiness.
财富认知 041 · Wealth Wisdom 041保险买的不是年龄,而是风险点击查看 ▾What you're buying isn't your age — it's your risk
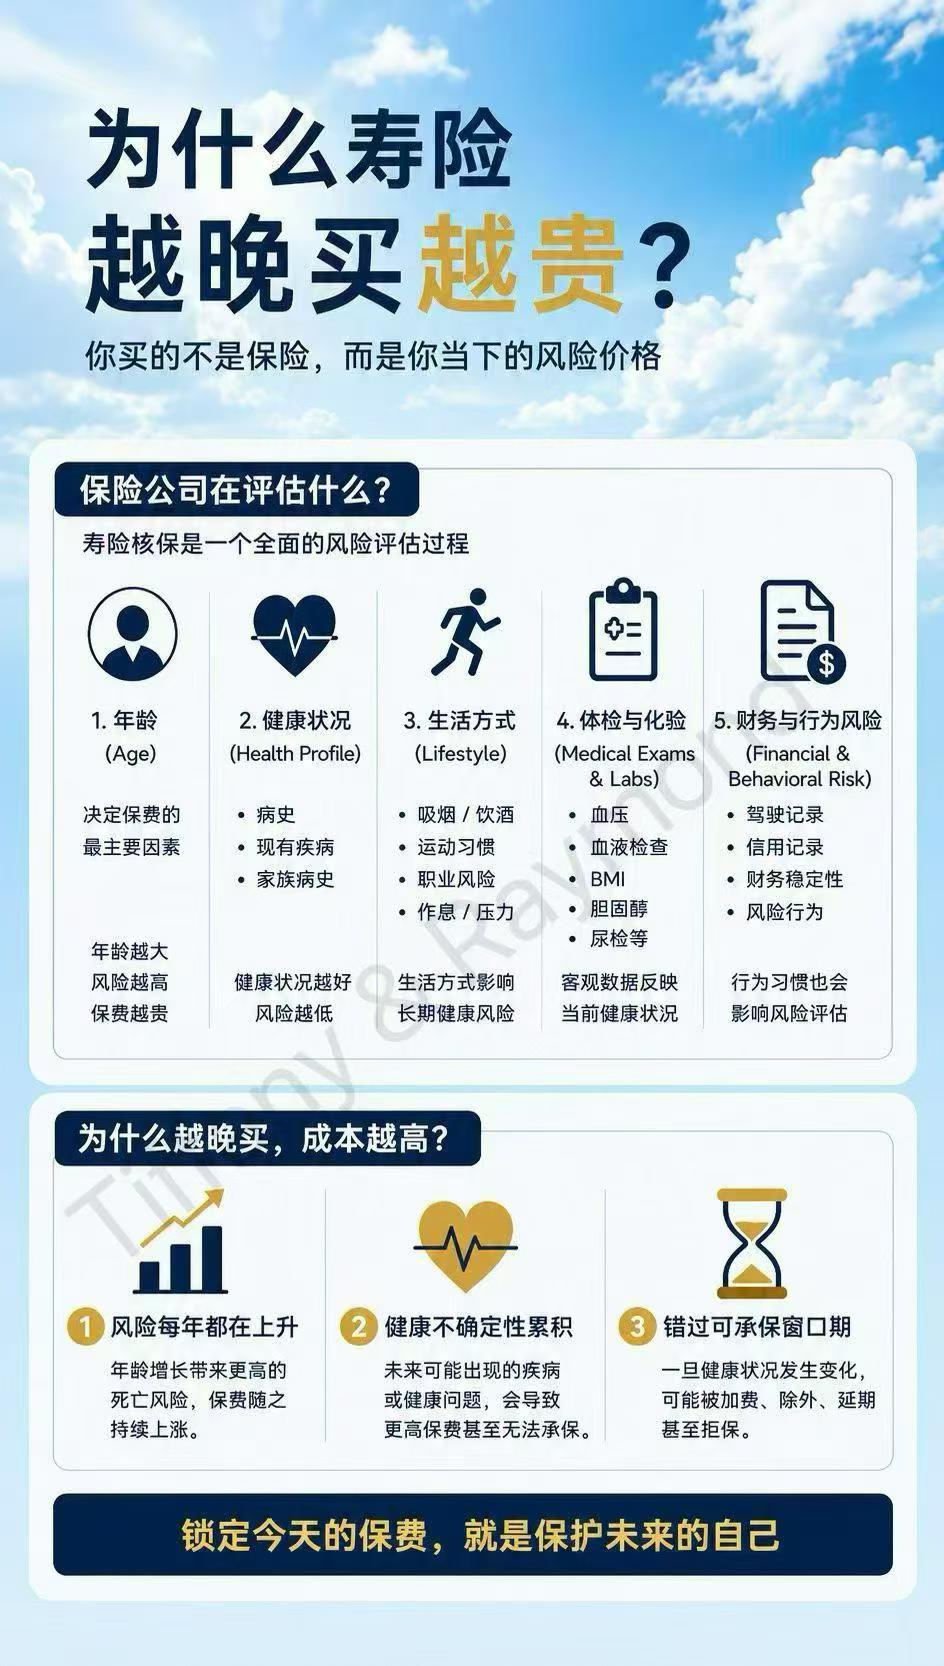
分享 →很多人问:为什么保费会随着年龄增长而上涨?因为保险买的不是年龄,而是风险。
Many people ask: why does the premium go up as you get older? Because what you're buying isn't your age — it's your risk.
年龄在变,健康状况在变,未来的不确定性也在增加,风险成本自然会越来越高。保险最大的优势,不是等需要时才买,而是在健康、年轻的时候提前规划。
Age changes, health changes, and future uncertainty keeps growing — so the cost of risk naturally keeps rising too. Insurance's biggest advantage isn't buying it once you need it, but planning ahead while you're still healthy and young.
早一点准备,不仅是为了省下一些保费,更是为了锁定人生中最低的风险成本。
Preparing earlier isn't just about saving on premiums — it's about locking in the lowest risk cost of your life.
种树最好的时间是十年前,其次是现在。保障也是如此。
The best time to plant a tree was ten years ago; the second best time is now. The same is true of protection.
财富认知 040 · Wealth Wisdom 040养老金月月到账更有底气点击查看 ▾A pension that lands every single month brings real peace of mind
分享 →有些安心,不是老了才突然拥有。
Some peace of mind doesn't just appear once you're old.
年轻时坚持规划几年,换来晚年几十年的从容。
A few years of committed planning while you're young buys you decades of ease later in life.
养老金月月到账更有底气。
A pension that lands every single month brings real peace of mind.
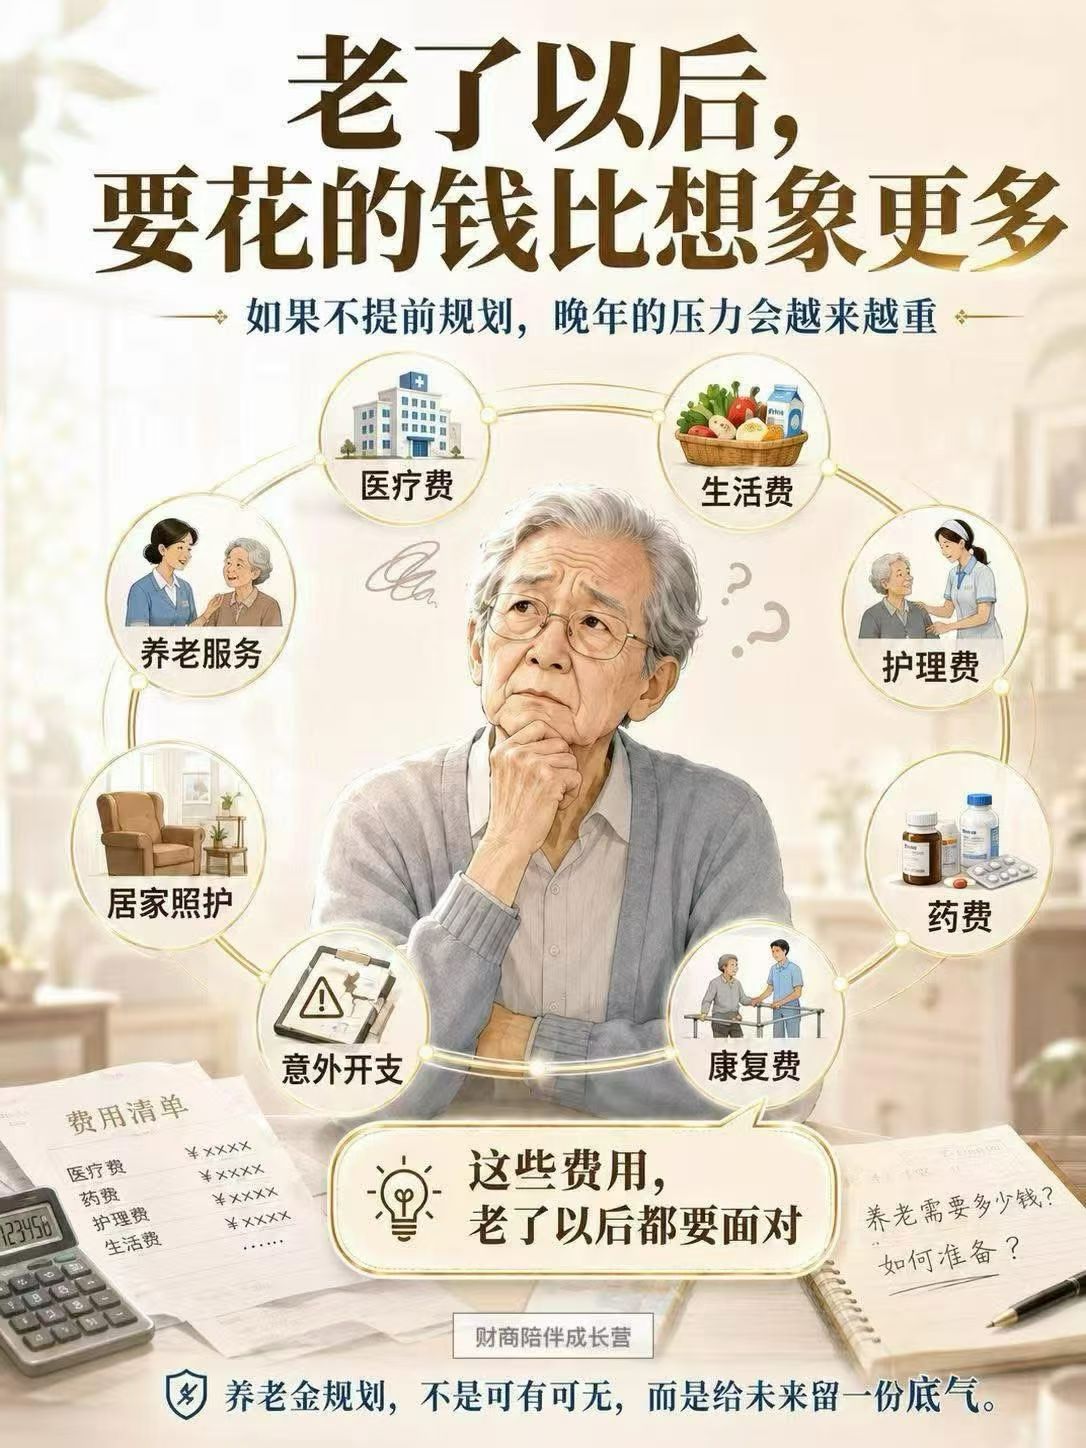
财富认知 039 · Wealth Wisdom 039养老规划是给未来多留一份底气点击查看 ▾Retirement planning is about leaving your future extra confidence
分享 →人老以后,花钱的地方真的不少。
Once you're older, there really are a lot of places money needs to go.
医疗费、生活费、护理费,每一项都需要提前想一想。
Medical costs, living expenses, care costs — every one of them needs to be thought through ahead of time.
养老规划是给未来多留一份底气。
Retirement planning is about leaving your future extra confidence.
财富认知 038 · Wealth Wisdom 038现在的规划,都是未来的底气点击查看 ▾The planning you do now is the confidence your future stands on
分享 →养老这件事,靠的不是别人。
Retirement isn't something you can rely on someone else for.
年轻时多准备一点,晚年就多一份从容。
Prepare a little more while you're young, and your later years gain that much more ease.
现在的规划,都是未来的底气。
The planning you do now is the confidence your future stands on.
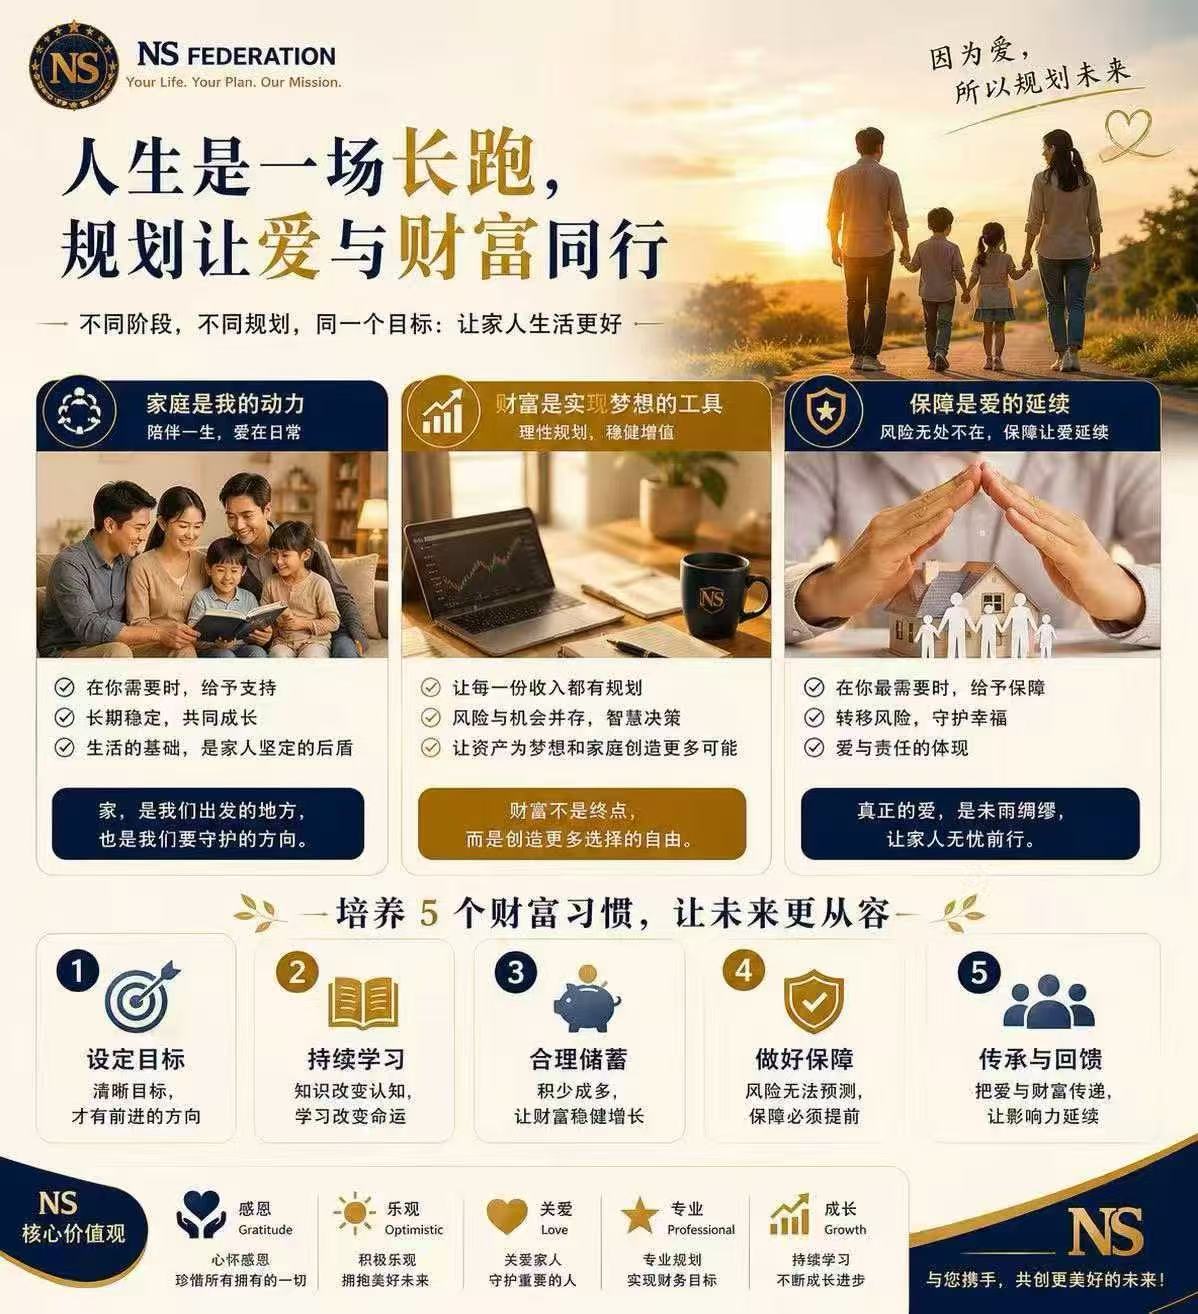
财富认知 037 · Wealth Wisdom 037真正的安全感,来自长期稳定的成长与准备点击查看 ▾True security comes from steady, long-term growth and preparation
分享 →人生不是短跑,而是一场长期的规划。
Life isn't a sprint — it's a long-term plan.
家庭、健康、财富与未来,都需要提前布局。
Family, health, wealth and the future all need to be positioned for ahead of time.
真正的安全感,来自长期稳定的成长与准备。
True security comes from steady, long-term growth and preparation.
财富认知 036 · Wealth Wisdom 036真正决定未来的,恰恰是那些"提前布局"的人点击查看 ▾More often than not, it's the people who position themselves early who truly determine the future
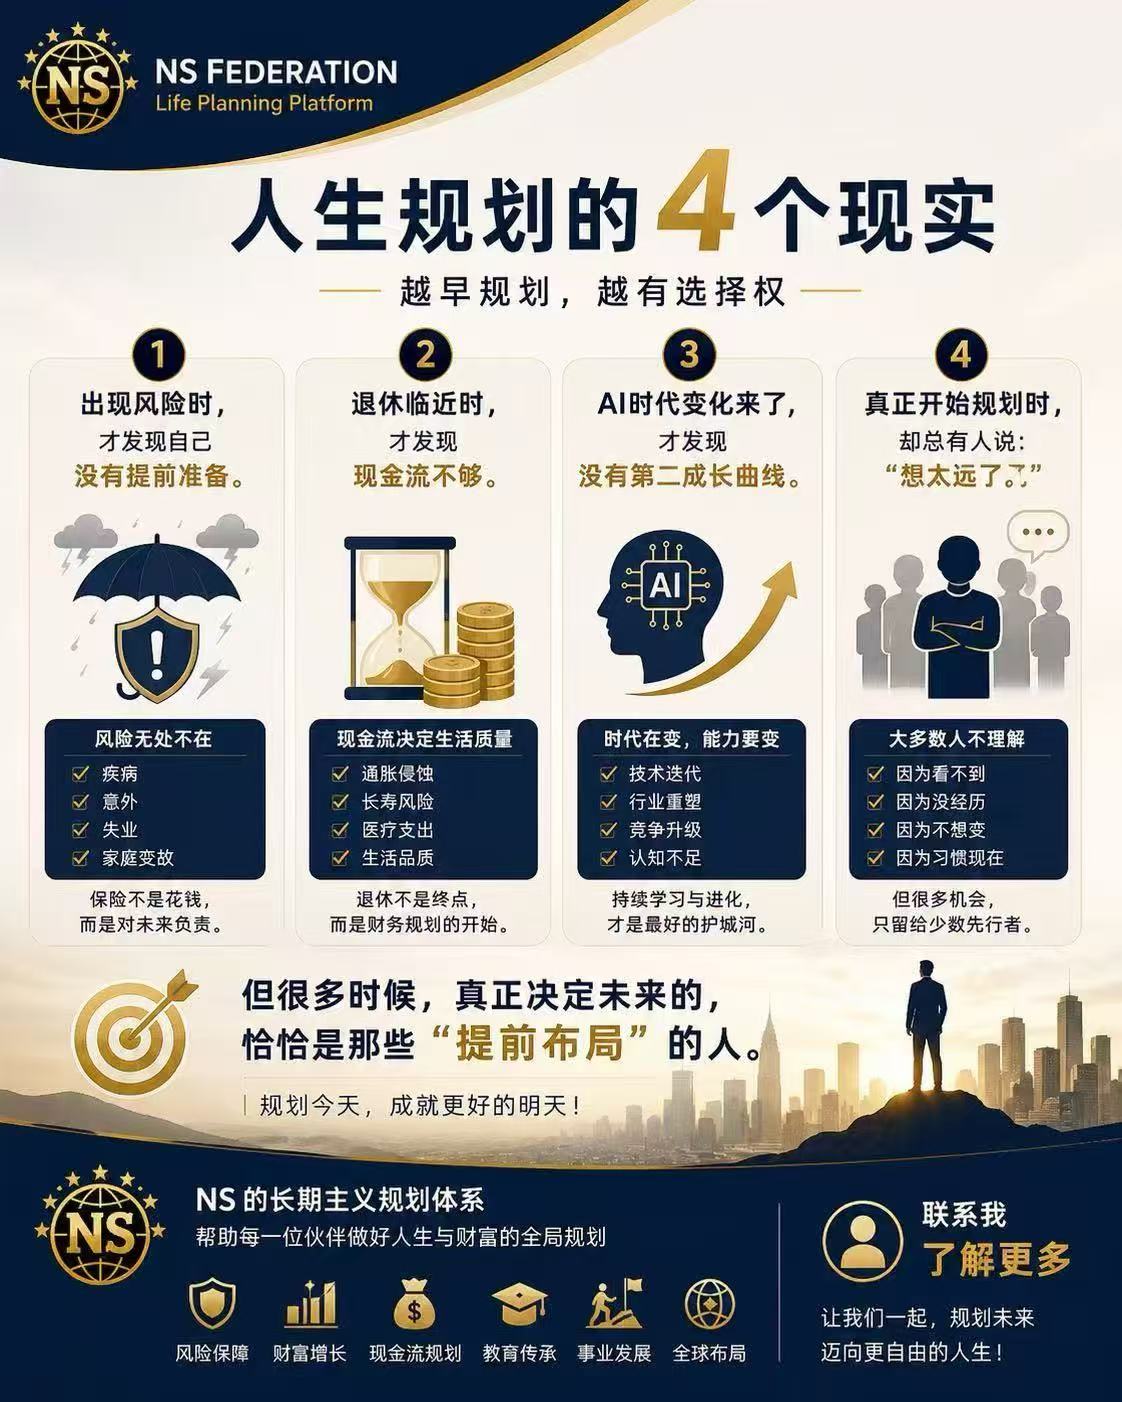
分享 →人生规划的 4 个现实——越早规划,越有选择权。
4 realities of life planning — the earlier you plan, the more choices you have.
出现风险时,才发现自己没有提前准备;退休临近时,才发现现金流不够;AI 时代变化来了,才发现没有第二成长曲线;真正开始规划时,却总有人说"想太远了"。
Risk strikes, and only then do you realize you weren't prepared. Retirement approaches, and only then do you realize your cash flow isn't enough. The AI era arrives, and only then do you realize you never built a second growth curve. And when you finally start planning, someone always says, "that's too far ahead to worry about."
但很多时候,真正决定未来的,恰恰是那些"提前布局"的人。规划今天,成就更好的明天!
But more often than not, it's the people who "position themselves early" who truly determine the future. Plan today, build a better tomorrow.
财富认知 035 · Wealth Wisdom 035AI 时代真正危险的,不是不努力,而是只有单一收入来源点击查看 ▾In the AI era, the real danger isn't a lack of effort — it's having only one source of income
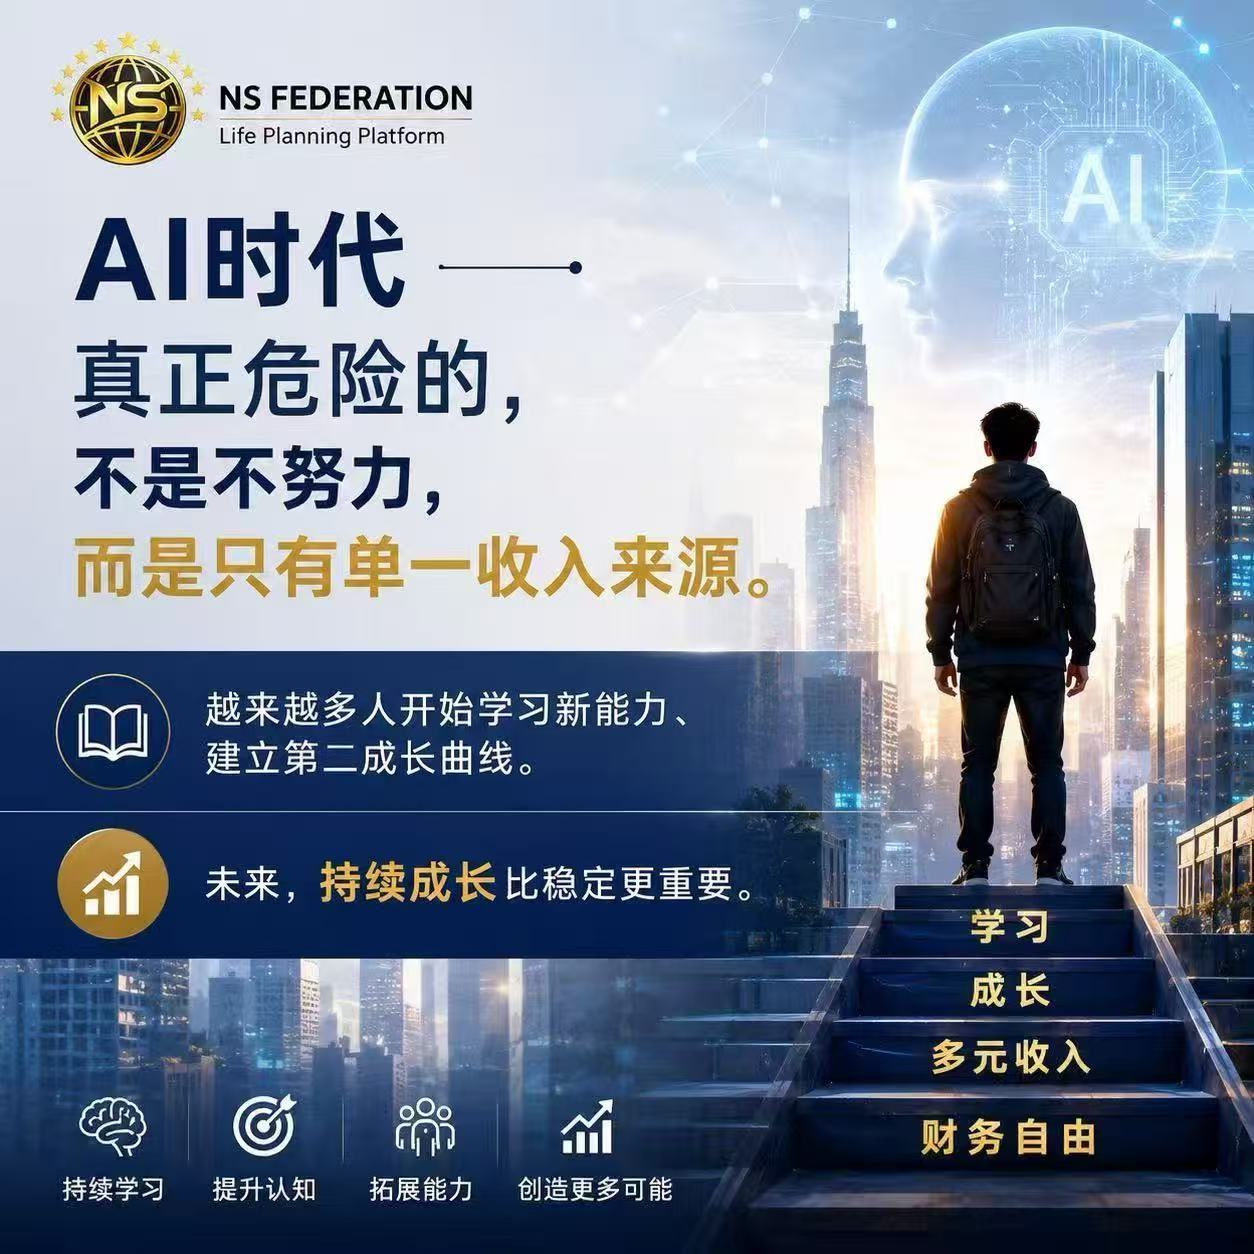
分享 →AI 时代真正危险的,不是不努力,而是只有单一收入来源。
In the AI era, the real danger isn't a lack of effort — it's having only one source of income.
越来越多人开始学习新能力、建立第二成长曲线。
More and more people are learning new skills and building a second growth curve.
未来,持续成长比稳定更重要。
In the future, continuous growth matters more than stability.
财富认知 034 · Wealth Wisdom 034聪明的人,把钱放对地方,让未来为自己工作点击查看 ▾Smart people put their money in the right place, and let the future work for them
分享 →懂得让钱生钱,还需要知道如何放对地方。
Knowing how to make money grow isn't enough — you also need to know where to put it.
大部分人不知道,作为美国最好的金融产品之一,美国人寿保险具有非常强大的理财功能,关键还免税。
Most people don't realize that U.S. life insurance — one of America's best financial products — has powerful wealth-building features, and crucially, it's tax-advantaged.
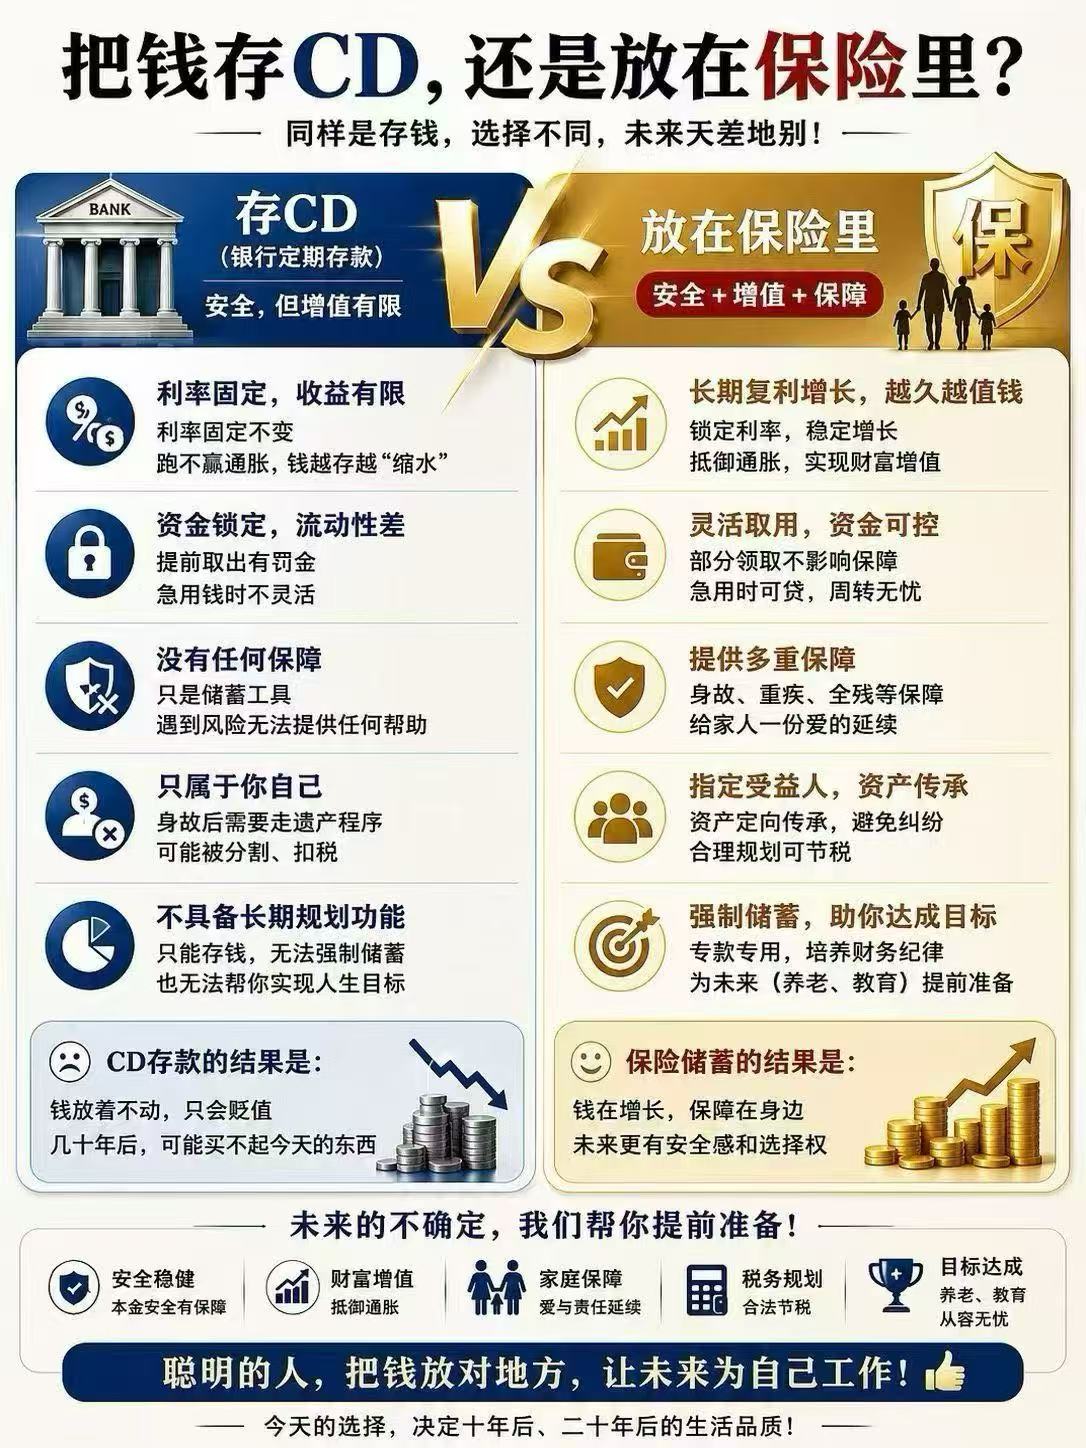
把钱存 CD,还是放在保险里? · CD or Insurance?
同样是存钱,选择不同,未来天差地别。CD 利率固定、资金锁定、没有任何保障;保险则长期复利增长、灵活取用、提供多重保障,还能指定受益人、实现资产传承。
Same act of saving, but a different choice makes a world of difference down the road. A CD locks in a fixed rate with funds tied up and no protection at all — insurance grows through long-term compounding, stays flexible to access, provides multiple layers of protection, and lets you name a beneficiary for wealth transfer.
聪明的人,把钱放对地方,让未来为自己工作。今天的选择,决定十年后、二十年后的生活品质。
Smart people put their money in the right place and let the future work for them. Today's choice determines your quality of life ten, twenty years from now.
财富认知 032 · Wealth Wisdom 032财富最大的秘密,不是收益率,而是时间点击查看 ▾The biggest secret of wealth isn't the rate of return — it's time
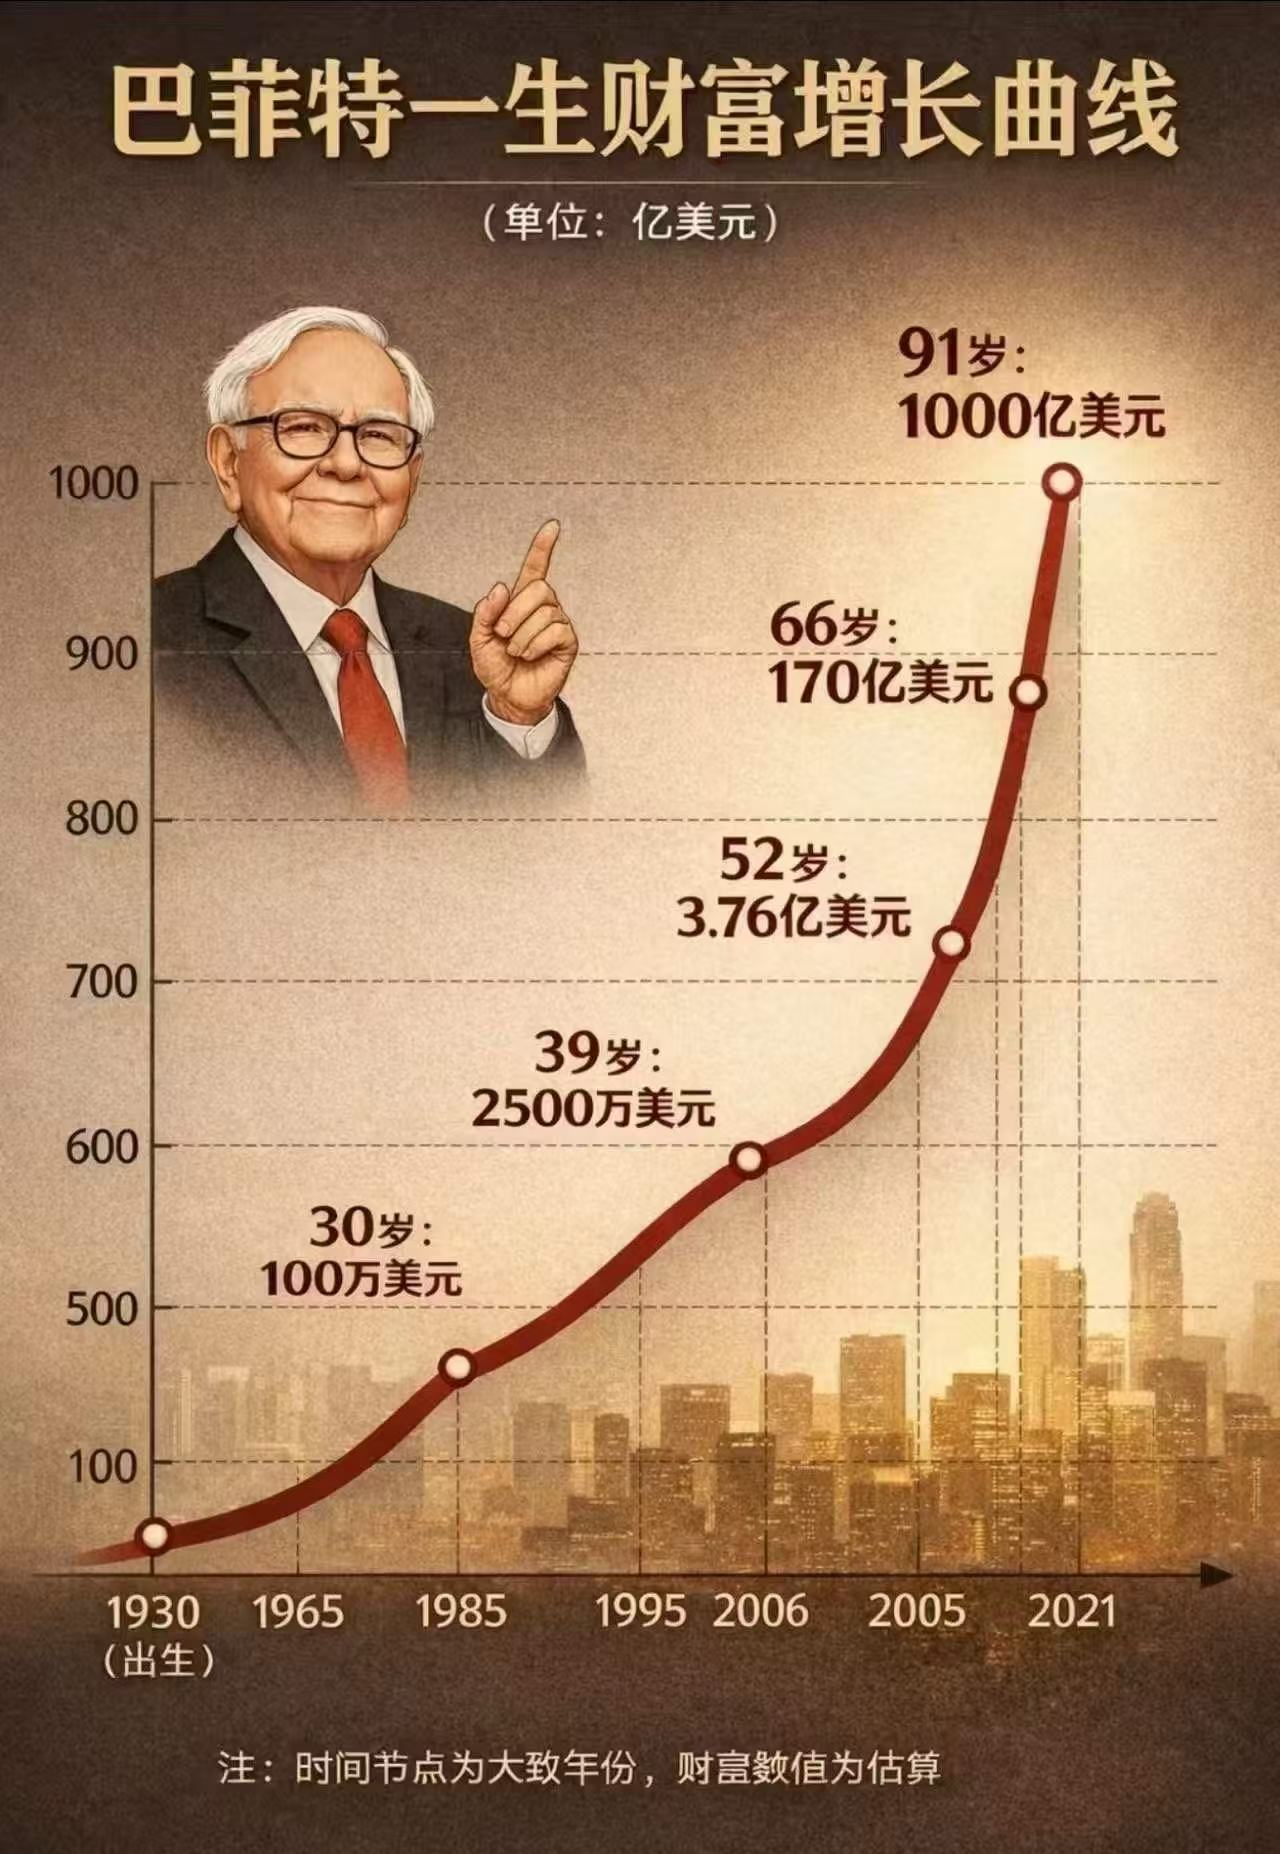
分享 →时间是最厉害的财富工具。
Time is the most powerful wealth tool there is.
巴菲特说:人生就像滚雪球,重要的是湿的雪和长长的坡。越早开始规划,时间越站在你这边。
Buffett once said: life is like a snowball — what matters is finding wet snow and a long hill. The earlier you start planning, the more time is on your side.
今天的问题 · Today's Question
如果给 20 岁的自己一个理财建议,你会说什么?
If you could give your 20-year-old self one piece of financial advice, what would it be?
财富最大的秘密,不是收益率,而是时间。
The biggest secret of wealth isn't the rate of return — it's time.
财富认知 031 · Wealth Wisdom 031现在规划未来,未来才有选择权点击查看 ▾Plan for the future today, so the future still has choices
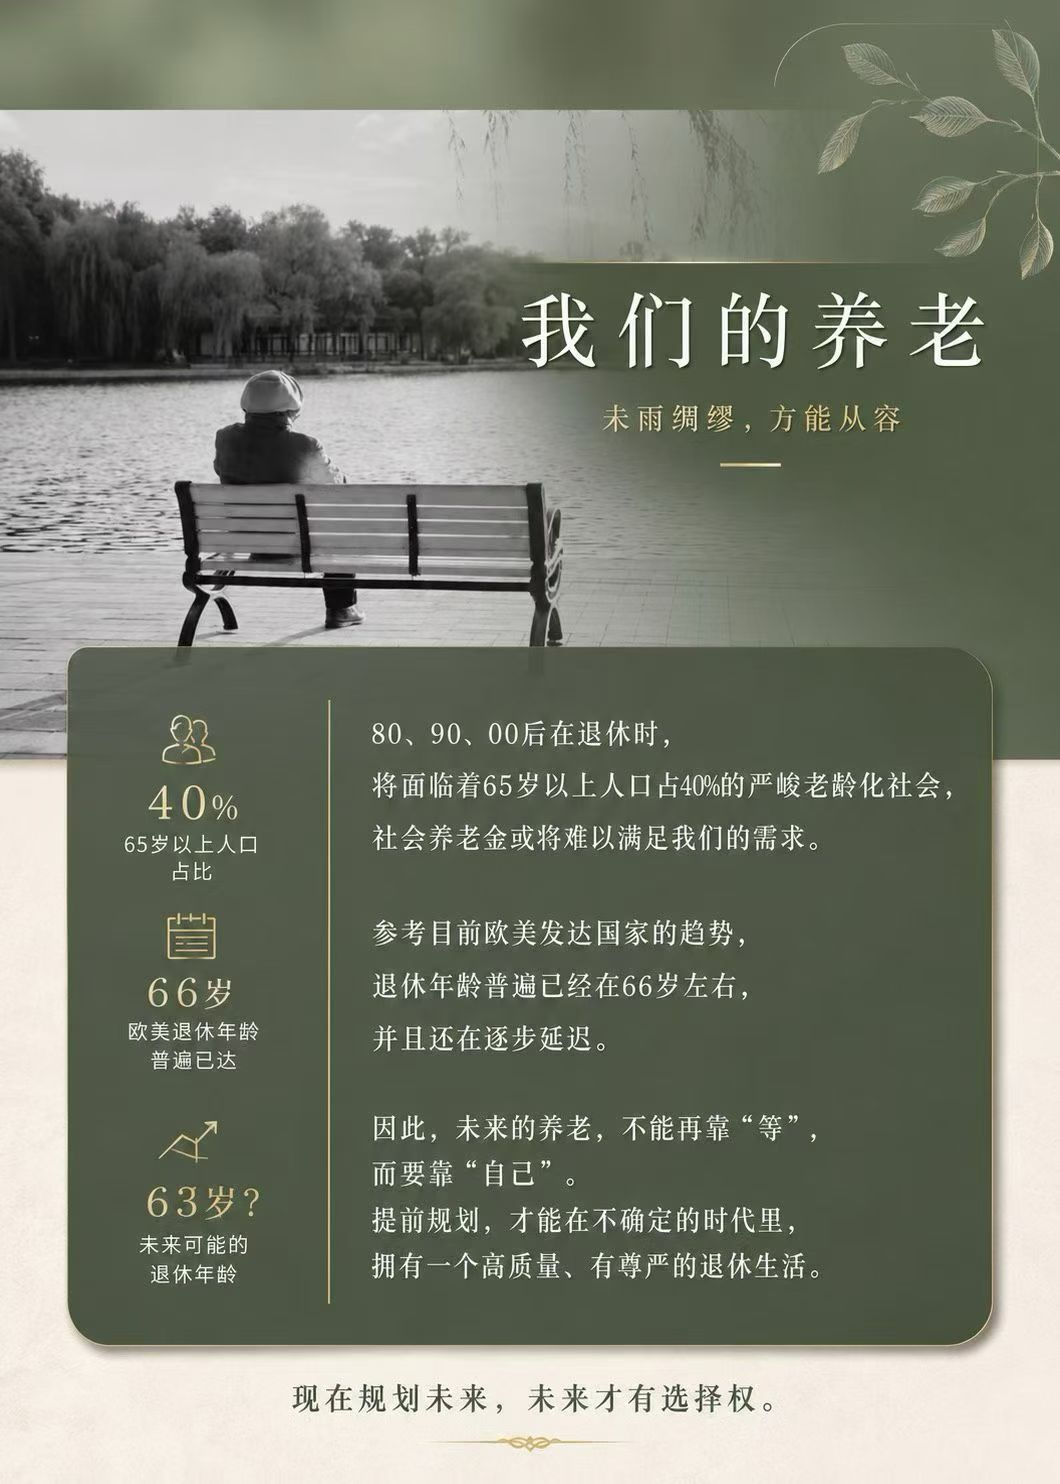
分享 →我们的养老——未雨绸缪,方能从容。
Our Retirement — only by preparing ahead can we face it with ease.
80、90、00 后在退休时,将面临着 65 岁以上人口占 40% 的严峻老龄化社会,社会养老金或将难以满足我们的需求。参考目前欧美发达国家的趋势,退休年龄普遍已经在 66 岁左右,并且还在逐步延迟。
By the time those born in the 80s, 90s and 2000s retire, they'll face a society where over 40% of the population is 65 or older — social security may struggle to meet everyone's needs. Looking at current trends in developed countries across Europe and the U.S., retirement ages are already around 66 on average, and still creeping later.
因此,未来的养老,不能再靠"等",而要靠"自己"。提前规划,才能在不确定的时代里,拥有一个高质量、有尊严的退休生活。
So the retirement of the future can no longer rely on "waiting" — it has to rely on "yourself." Only by planning ahead can you have a high-quality, dignified retirement in an uncertain era.
现在规划未来,未来才有选择权。
Plan for the future today, so the future still has choices.
财富认知 030 · Wealth Wisdom 030财富不是拥有多少,而是风雨来临时,还能剩下多少点击查看 ▾Wealth isn't how much you have — it's how much is left when the storm comes
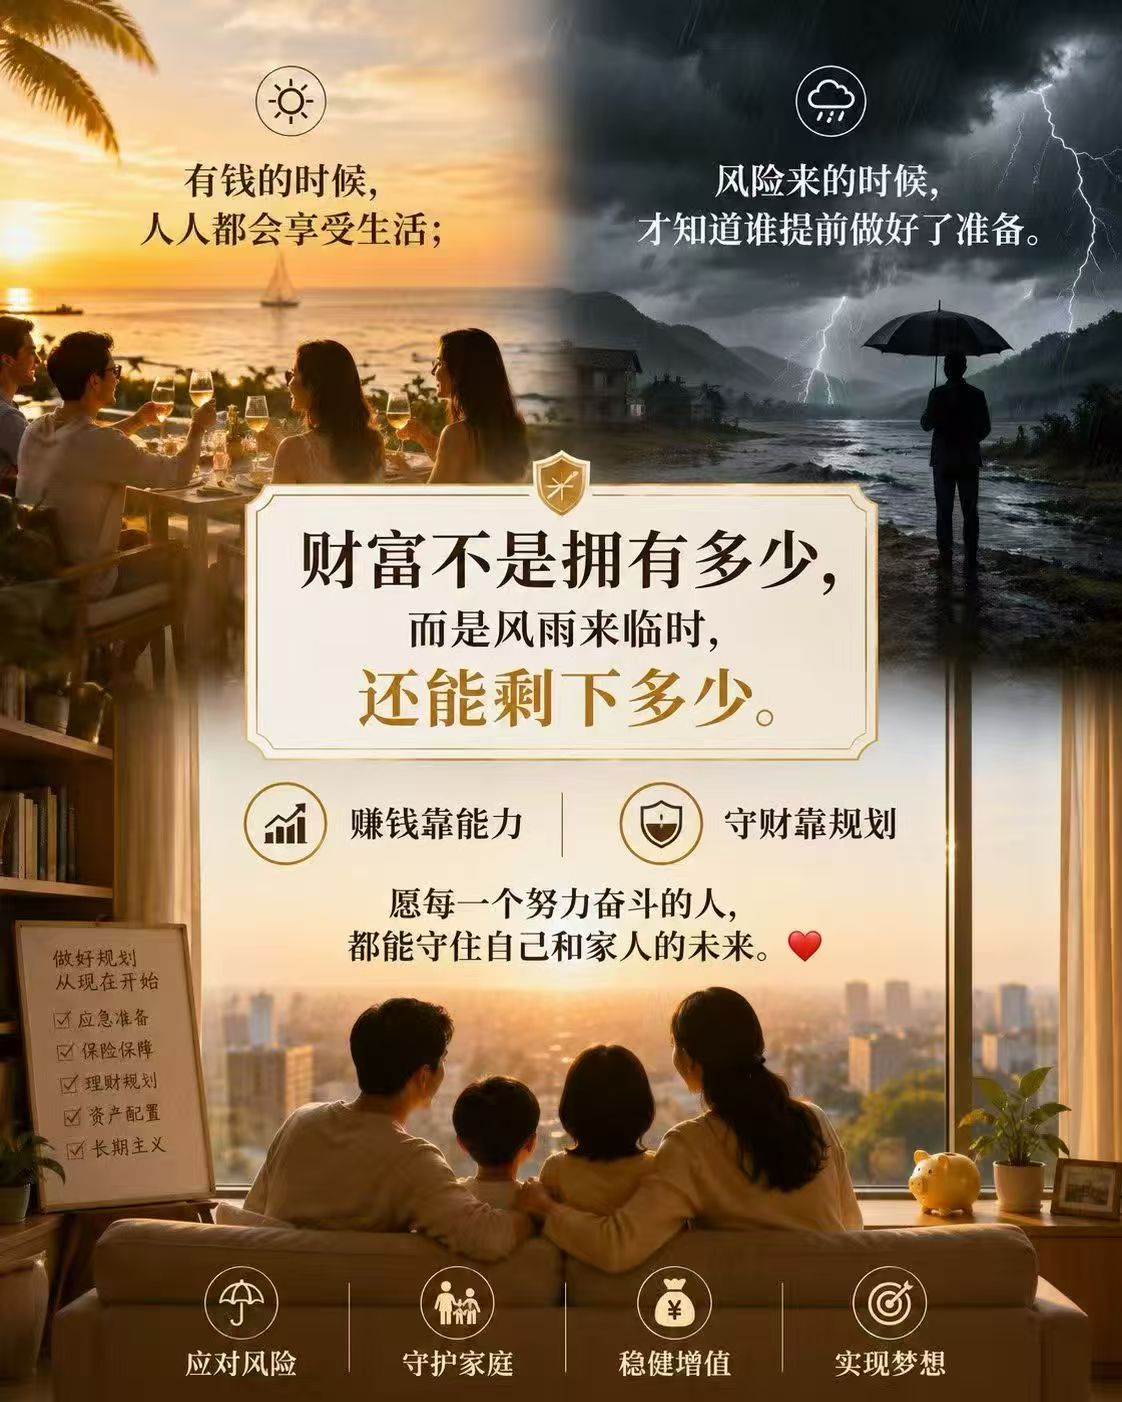
分享 →有钱的时候,人人都会享受生活;风险来的时候,才知道谁提前做好了准备。
When there's money, everyone knows how to enjoy life; it's only when risk arrives that you find out who actually prepared ahead of time.
财富不是拥有多少,而是风雨来临时,还能剩下多少。
Wealth isn't about how much you have — it's about how much is left when the storm comes.
赚钱靠能力,守财靠规划。愿每一个努力奋斗的人,都能守住自己和家人的未来。
Earning takes ability; keeping it takes planning. May every hardworking person be able to protect their own future and their family's.
财富认知 029 · Wealth Wisdom 029选择正确,才会活得越老越有底气点击查看 ▾The right choice is what lets you grow older with confidence
分享 →美国婴儿潮出生的人,如今已过花甲之年,平均每天有上万人退休,社安(Social Security)负担不堪重负。
America's baby boomers have now passed sixty — on average, tens of thousands retire every single day, and Social Security is buckling under the strain.
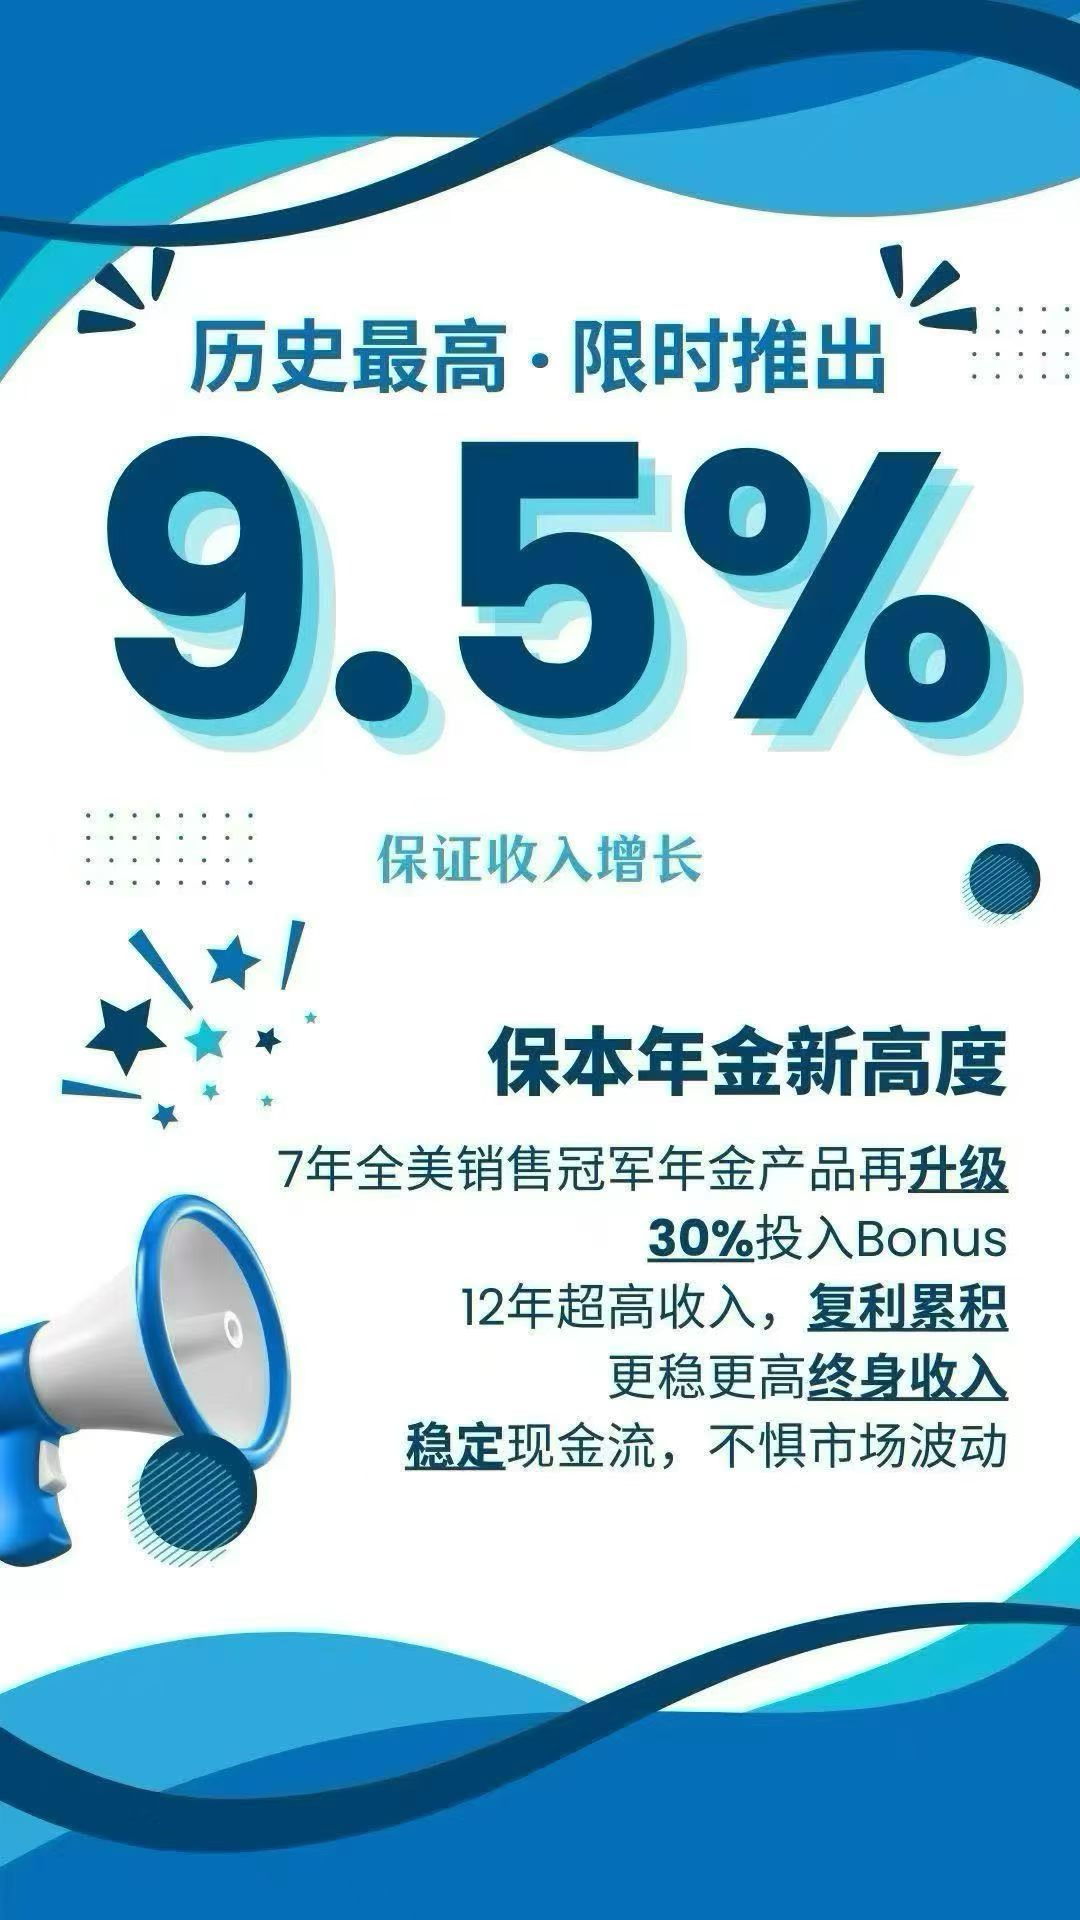
上周股市大跌,前期天天歌舞升平赚钱的股票账户,一下子回到解放前,401K 账户又缩水了。然而,您是否了解年金理财产品这个解决方案——保底安全,只涨不跌,9.5% 复利滚动,【保证】为您提供源源不断、与生命等长的现金流。
Last week's market plunge wiped out weeks of gains in a flash, and 401(k) balances shrank once again. But have you looked into annuities as a solution? Principal-protected, only up and never down, compounding at 9.5% — guaranteed to provide a steady stream of income that lasts as long as you do.
退休最大的风险,从来不是赚得不够,而是退休之后,还有二三十年的人生要过。趁今天还有收入,为未来的自己建立一份永不退休的收入。
The biggest risk in retirement was never earning too little — it's that after you retire, there are still two or three more decades of life ahead. While you still have income today, build yourself an income that never retires.
选择正确,才会活得越老越有底气。
The right choice is what lets you grow older with confidence.
财富认知 028 · Wealth Wisdom 028股市好的时候,大家都觉得自己很会投资;连续跌几天,才知道守住本金有多重要点击查看 ▾When markets are booming, everyone feels like a great investor — a few down days reveal how much protecting your principal really matters
分享 →股市好的时候,大家都觉得自己很会投资;连续跌几天,才知道守住本金有多重要。
When the market's booming, everyone thinks they're a great investor — a few days of losses is what reveals how much protecting your principal really matters.
这几天股市连续下跌,一位有63年投资经验的客户,短短几天就亏了十几万。他说,问题往往不是看不懂市场,而是人性里的贪婪让人舍不得及时止损——这正是90%散户最终亏钱的原因。
The market's been falling for days, and a client with 63 years of investing experience lost over a hundred thousand in just that short stretch. He said the problem is rarely that people don't understand the market — it's the greed in human nature that keeps them from cutting losses in time. That's exactly why 90% of retail investors end up losing money.
也常有人拿人寿、年金和股票比较,觉得回报不够激进。但三者定位本就不同:股票追求更高增长、也伴随更大波动;人寿、年金同样跟随指数表现,长期平均年化收益约10%左右(以具体产品条款为准),同时设有0%保底机制——指数为负的年份不倒扣本金,涨跌之间更容易拿得住。
People often compare life insurance, annuities and stocks and feel the returns aren't aggressive enough. But the three serve different purposes: stocks chase higher growth and come with bigger swings; life insurance and annuities also track index performance, with a long-term average annual return around 10% (subject to the specific product), while carrying a 0% floor — in years the index is negative, your principal isn't deducted, making the ups and downs easier to hold through.
人寿保险早已从单一的身故保障,发展成一个多功能的金融工具:理财增值、生前与身故保障、资产隔离、财富传承,甚至免税资产累积,都能整合在同一张保单里——这也是为什么真正的富人,往往更愿意把人寿保险当作资产配置里的核心工具之一。
Life insurance has evolved far beyond a simple death benefit into a multi-functional financial tool — wealth accumulation, living and death benefit protection, asset protection, wealth transfer, and even tax-advantaged growth can all be built into a single policy. That's exactly why the truly wealthy are often more willing to make life insurance a core part of their financial planning.
退休最终靠的不是账户涨得多快,而是能不能提供长期稳定的现金流——这才是理财规划真正该关注的重点。
What retirement ultimately depends on isn't how fast your account grows, but whether it can provide a stable, long-term cash flow — that's the real thing financial planning should focus on.
财富认知 027 · Wealth Wisdom 027提前规划养老,不是因为害怕变老,而是希望活得体面、从容、有尊严点击查看 ▾Planning for retirement early isn't about fearing old age — it's about living with dignity, ease and grace
分享 →提前规划养老,不是因为害怕变老,而是希望未来的每一天,都活得体面、从容、有尊严。
Planning for retirement early isn't because we're afraid of growing old — it's because we want every day ahead to be lived with dignity, ease, and grace.
我们努力半生,不是为了晚年看人脸色,而是能体面养老,不拖累下一代;提前规划,是对自己负责,也是对家人最大的爱。
We work hard for half a lifetime not so we have to watch others' faces in old age, but so we can age with dignity and never become a burden to the next generation — planning ahead is both a responsibility to ourselves and the greatest gift of love to our family.
人生下半场,拼的不是赚钱的能力,而是规划的智慧。
In the second half of life, what matters isn't the ability to earn — it's the wisdom to plan.
财富认知 026 · Wealth Wisdom 026AI 时代,个人能力的边界,正在被重新定义点击查看 ▾In the age of AI, the boundaries of individual capability are being redrawn
分享 →AI 时代,个人能力的边界,正在被重新定义。
In the age of AI, the boundaries of individual capability are being redrawn.
过去,财富积累很大程度上依赖资本规模、团队协作与信息壁垒;而今天,AI 让一个人也能调动过去需要一整个团队才能完成的能力——研究、创作、运营、变现,都可以由一个人加上合适的工具来完成。
In the past, building wealth depended heavily on capital scale, team collaboration and access to information. Today, AI lets a single person marshal capabilities that once required an entire team — research, content creation, operations and monetization can all be handled by one person paired with the right tools.
这意味着财富积累的方式正在改变:不再只是"用别人的时间和资本",而是"用AI放大自己的时间和判断力"。谁能更早学会与AI协作,谁就更有机会在新的规则里占据先机。
This means the way wealth is built is shifting — no longer only "leveraging other people's time and capital," but "using AI to amplify your own time and judgment." Those who learn to work alongside AI earlier stand a better chance of getting ahead under these new rules.
真正的财富机会,往往留给愿意先突破自己能力边界的人。
Real opportunity tends to favor those willing to break through their own limits first.
财富认知 025 · Wealth Wisdom 025复利最大的敌人,不是低回报,而是中途的中断点击查看 ▾The biggest enemy of compounding isn't low returns — it's interruption
分享 →复利最大的敌人,不是低回报,而是中途的中断。
The biggest enemy of compound interest isn't a low return — it's an interruption along the way.
每一次提前支取、每一次因为恐慌而清仓,本质上都是在按下复利的"重启键",让原本该滚雪球的时间,重新从零开始计算。
Every early withdrawal, every panic-driven sell-off, is essentially hitting compounding's "reset button" — forcing the snowball that should have kept rolling to start counting from zero again.
真正让复利发挥威力的,从来不是找到最高回报的工具,而是找到一个你愿意长期持有、不轻易中断的工具。
What truly unlocks the power of compounding was never about finding the highest-return tool — it's about finding one you're willing to hold for the long run, without interruption.

财富认知 024 · Wealth Wisdom 02472法则:用72除以年化收益率,算出钱翻倍要几年点击查看 ▾The Rule of 72: how many years until your money doubles
分享 →用72除以年化收益率,就是你的钱翻倍所需要的年数——这是判断一个投资工具好坏最快的方法之一。
Divide 72 by your annual rate of return, and you get roughly how many years it takes your money to double — one of the fastest ways to judge whether an investment tool is worth your time.
年化6%,大约12年翻倍;年化3%,则需要24年。同样是"稳健增长",翻倍速度可能相差一倍,而这背后的差距,最终决定了你退休时资产的量级。
At 6% annual growth, your money roughly doubles in 12 years; at 3%, it takes 24. Both may be called "steady growth," but the doubling speed can differ by 2x — and that gap ultimately decides the scale of your assets at retirement.
72法则的价值,不在于精确计算,而在于让你在几秒钟内,判断一个理财方案到底值不值得你把钱放进去。
The value of the Rule of 72 isn't precision — it's letting you judge, in seconds, whether a financial plan is actually worth putting your money into.

财富认知 023 · Wealth Wisdom 023复利不只在银行账户里,也在你的健康、关系与习惯里点击查看 ▾Compounding lives in your health and habits too, not just your bank account
分享 →复利不只存在于银行账户里,它也存在于你的健康、关系与习惯里。
Compounding doesn't just live in a bank account — it lives in your health, your relationships and your habits too.
每天进步1%,一年后你会强大37倍;每天退步1%,一年后几乎归零。财富、健康、能力,本质上遵循同一套复利逻辑:微小的正确选择,长期持续,就是巨大的差距。
Improve by just 1% a day, and in a year you're 37 times stronger; decline by 1% a day, and in a year you're close to zero. Wealth, health and skill all follow the same compounding logic — small, correct choices, sustained over time, become an enormous gap.
真正拉开人与人差距的,从来不是某个决定性的瞬间,而是日复一日、看似无关紧要的复利选择。
What truly separates people was never a single decisive moment — it was the ordinary, seemingly unimportant compounding choices, made day after day.

财富认知 022 · Wealth Wisdom 022晚开始10年,往往要多存两倍的钱才能达到同样目标点击查看 ▾Starting ten years late often means saving twice as much
分享 →晚开始10年,往往不是少赚10年的钱,而是需要多存两倍的钱,才能达到同样的目标。
Starting ten years late usually doesn't just mean missing ten years of growth — it often means having to save twice as much to reach the same goal.
复利前期的增长非常缓慢,很多人因此低估它、甚至半途放弃;但复利真正惊人的部分,永远发生在后段——这也是为什么"开始的时间"比"投入的金额"更关键。
Compounding grows painfully slowly at first, which is why many people underestimate it — or give up halfway. But the truly dramatic growth always happens in the later stretch, which is exactly why "when you start" matters more than "how much you start with."
越早开始,需要的努力越小;越晚开始,需要的代价越大。这是复利最公平、也最残酷的规则。
The earlier you start, the less effort it takes; the later you start, the higher the price. This is compounding's fairest — and most unforgiving — rule.

财富认知 021 · Wealth Wisdom 021今天的1万元,和20年后的1万元,从来不是同一个1万元点击查看 ▾$10,000 today and in 20 years were never the same $10,000
分享 →今天的1万元,和20年后的1万元,从来不是同一个1万元。
$10,000 today and $10,000 in twenty years were never the same $10,000.
通货膨胀会持续稀释货币的购买力,而复利则能让资产的实际价值持续增长。同一笔钱,放在活期存款里贬值,放在合适的资产里增值——差别就在于有没有让时间为你工作。
Inflation steadily erodes purchasing power, while compounding steadily grows real value. The same sum of money loses value sitting in a checking account, and gains value in the right asset — the difference is simply whether you let time work for you.
财富规划的本质,就是尽早做出决定,把不确定的未来,变成可以被时间放大的确定性。
The essence of financial planning is making the decision early — turning an uncertain future into a certainty that time can amplify.

财富认知 020 · Wealth Wisdom 020富人先建立被动收入,普通人先工作才想起被动收入点击查看 ▾The wealthy build passive income first; most people work first
分享 →富人先建立被动收入,再考虑要不要工作;普通人先工作,才想起要不要建立被动收入。
The wealthy build passive income first, then decide whether to work; most people work first, and only later think about building passive income.
主动收入用时间换钱,一旦停止工作,收入也随之停止;被动收入则是让资产、系统或工具持续为你产生现金流,即使你在睡觉,它依然在运转。
Active income trades time for money — the moment you stop working, the income stops too. Passive income means your assets, systems or tools keep generating cash flow for you, even while you sleep.
建立被动收入的过程,往往枯燥且缓慢,这也是为什么大多数人选择放弃、只有少数人真正实现财务自由。
Building passive income is often a slow, unglamorous process — which is exactly why most people give up along the way, and only a few ever reach true financial freedom.

财富认知 019 · Wealth Wisdom 019世界第八大奇迹,不是金字塔,而是复利点击查看 ▾The eighth wonder of the world isn't the pyramids — it's compound interest
分享 →世界第八大奇迹,不是金字塔,而是复利。
The eighth wonder of the world isn't the pyramids — it's compound interest.
爱因斯坦说复利是世界第八大奇迹,理解它的人赚它,不理解的人付它。财富积累的秘密,从来不是一夜暴富,而是让钱在时间里不断为你工作。
Einstein reportedly called compound interest the eighth wonder of the world — those who understand it earn it, those who don't pay it. The real secret of building wealth was never overnight riches — it's letting your money keep working for you, over time.
同样的本金,提早10年开始,最终结果可能是完全不同的数量级。时间,才是复利真正的引擎。
The same starting amount, begun ten years earlier, can end up an entirely different order of magnitude. Time — not the amount — is the true engine of compound interest.

财富认知 018 · Wealth Wisdom 018退休看的不是存多少钱,而是资产能否持续产生现金流点击查看 ▾Retirement is about whether assets can generate sustained cash flow
分享 →退休不是看你有多少钱,而是看你的资产能不能持续产生现金流,覆盖你的生活成本。
Retirement isn't about how much money you have — it's about whether your assets can generate sustained cash flow to cover your living costs.
真正决定财务自由的不是资产总额,而是:
可持续现金流 ≥ 每年的生活支出。
What truly determines financial freedom isn't your total assets, but this:
sustainable cash flow ≥ your annual living expenses.
因此,有的人拥有500万美元却生活成本很高,仍会有压力;而有的人拥有100万美元、生活简单、支出稳定,也可能已经实现了财务自由。
So some people may have $5 million yet still feel pressure because of a high cost of living, while others with $1 million — living simply, with stable expenses — may have already achieved financial freedom.

财富认知 017 · Wealth Wisdom 017保险不是买完就结束,而是需要长期管理点击查看 ▾Insurance isn't done once bought — it needs ongoing management
分享 →☘️有人一直以为自己的保单什么都能赔,直到重大疾病来临,才发现原来没有生前福利,没有重疾保障!
Some people always assumed their policy would cover everything — until a critical illness struck, only to discover there was no living benefit, no critical illness coverage at all!
✅有人因为是亲戚朋友介绍,觉得放心,就签了保单,却很多年都不知道自己到底买了什么?
Some signed a policy simply because a relative or friend referred it and it felt trustworthy — yet years later still don't know what they actually bought.
✅也有人年轻时觉得身体好、不着急规划,等健康亮起红灯,再想买的时候,已经失去了最好的机会…
Others felt healthy when young and saw no urgency to plan — by the time their health took a turn and they wanted coverage, the best window had already closed.
☘️保险,不是买完就结束,而是需要长期管理。
Insurance isn't something that ends once you buy it — it needs ongoing management.
家庭会成长,
收入会变化,
孩子会长大,
退休规划会调整,
保障也应该随着人生不同阶段不断优化升级。
Families grow,
income changes,
children grow up,
retirement plans shift,
and coverage should keep being optimized and upgraded at every life stage.
也许,你需要的不是再买一份,而是找专业的经纪人帮你评估确认它,是否需要及时升级换代,最有效的保护未来的自己和家人。
Maybe what you need isn't another policy — it's a professional broker to help review and confirm whether yours needs an upgrade, to most effectively protect your future self and family.

财富认知 016 · Wealth Wisdom 016中年以后,别再赌健康和晚年一定无忧点击查看 ▾After midlife, stop betting your health and later years will be worry-free
分享 →中年以后,
别再赌身体一直健康,
也别赌晚年一定无忧。
After midlife,
stop betting that your health will always hold up,
and stop betting that your later years will be worry-free.
趁还有选择的时候,
把该规划的提前规划好。
While you still have a choice,
plan ahead for what needs to be planned.

财富认知 015 · Wealth Wisdom 015为什么连美国大型银行,也把大笔资金配置到人寿保险?点击查看 ▾Why do even large U.S. banks hold billions in life insurance?
分享 →总有人说:"钱放银行最安全。"
People often say: "Keeping your money in the bank is the safest thing to do."
但有趣的是,美国很多大型银行,自己却把几十亿、上百亿美元配置到人寿保险资产。
But interestingly, many large U.S. banks themselves hold billions — even tens of billions of dollars — in life insurance assets.
银行之所以这样做,不是因为保险"神奇",而是因为它具有长期、稳定、税务优势等特点,能成为资产配置的一部分。
Banks do this not because insurance is "magical," but because of its long-term stability and tax advantages, which make it a valuable part of asset allocation.
所以,真正值得思考的不是"买不买保险",而是为什么连银行都在配置它?🤔
So the real question isn't "should you buy insurance" — it's why even the banks are allocating to it? 🤔
看懂的人,会多一个财富规划的思路;
看不懂的人,可能只是把保险当成了一张保单。
Those who understand it gain another angle on wealth planning;
those who don't may simply see insurance as just a policy.

财富认知 014 · Wealth Wisdom 014全球富人最爱配置的免税资产是什么?点击查看 ▾What tax-free asset do the world's wealthy love most?
分享 →您知道吗?全球富人最爱配置的免税资产是什么吗?
Did you know? What's the tax-free asset the world's wealthy love to hold most?
IUL(指数型万能寿险),她集储蓄、保障、免税、传承等功能,更像一个万能金融工具:
IUL (Indexed Universal Life insurance) combines savings, protection, tax advantages and legacy planning — more like an all-purpose financial tool:
✔ 增长(核心)
Growth (Core)
与市场指数(如 S&P 500)挂钩,保底复利增长,中长期历史表现常被参考为年均约8%上下。
Linked to a market index (e.g. S&P 500); compound growth with a downside floor; medium-to-long-term historical performance is often cited at around 8% annually.
✔ 保障
Protection
提供身故保障及免费附加重疾、长期护理等功能。
Provides a death benefit, plus free add-ons for critical illness and long-term care.
✔ 税务
Tax
属于美国体系下的免税资产。
A tax-free asset within the U.S. system.
✔ 传承
Legacy
结构简单,实现高效财富传承。
Simple structure that enables efficient wealth transfer.
它已不仅是保险,更是——增长 + 保障 + 税务 + 传承 的组合金融工具。
It's no longer just insurance — it's a combined tool of growth + protection + tax + legacy.
很多专业人士,会把它当作:
🌿 个人及家庭的资金蓄水池 / 个人银行
Many professionals treat it as:
🌿 a personal and family cash reservoir / your own bank.
它不是用来"买"的,而是用来长期规划人生与资产的工具。
It's not something you simply "buy" — it's a tool for long-term life and asset planning.
IUL是美国发明的金融工具,全球销量第一,杠杆是大陆的5倍,台湾的3倍,香港的2倍,也不要什么门槛,您有了解吗?在美国的朋友们都应该百般珍惜,充分利用配置。
IUL is a financial tool invented in the U.S., ranked first in global sales, with leverage 5x that of mainland China, 3x that of Taiwan, and 2x that of Hong Kong — with no real entry barrier. Do you understand it? Friends in the U.S. should treasure it and make full use of it.

财富认知 013 · Wealth Wisdom 013你了解吗?银行/退休金账户的钱可以转到年金账户点击查看 ▾Did you know? 401k/IRA funds can transfer into an annuity account
分享 →你了解吗?
Did you know?
银行 + 退休金账户的钱(401k/IRA)可以转到年金账户。
Money in a bank account or a retirement account (401k/IRA) can be transferred into an annuity account.
✅ 收益比银行高、风险比基金低,保本不亏;
✅ 保险公司保证每年发退休金,活多久发多久;
✅ 抗通货膨胀
✅ Higher returns than a bank, lower risk than funds — principal protected;
✅ The insurance company guarantees annual retirement payouts for as long as you live;
✅ Inflation-resistant

财富认知 012 · Wealth Wisdom 012财富自由不是用时间换钱,而是积累能产生被动收入的资产点击查看 ▾Financial freedom means building assets that generate passive income
分享 →很多人都想实现财富自由,但如果对"财富自由"的定义不清楚,其实很难真正实现。
Many people want financial freedom, but without a clear definition of what it actually means, it's hard to truly achieve it.
真正的财富自由,不是一辈子用时间和体力换钱,而是不断累积能够持续带来被动收入的资产。
True financial freedom isn't spending a lifetime trading time and effort for money — it's steadily building assets that keep generating passive income.
因为不是所有资产都能让人自由,真正重要的,是那些即使你不工作,依然能持续产生现金流的资产。
Not every asset sets you free. What truly matters are the assets that keep generating cash flow even when you're not working.
所以越早建立财富认知、越早开始累积这类资产,人生就越拥有选择权与自由。
So the earlier you build financial awareness and start accumulating these assets, the more choice and freedom your life will have.

财富认知 011 · Wealth Wisdom 011真正拉开差距的,不是努力,而是有没有提前规划点击查看 ▾What sets people apart isn't effort — it's whether they planned ahead
分享 →很多时候,真正拉开人与人差距的,不是努力,而是有没有提前规划。
Often, what truly sets people apart isn't effort — it's whether they planned ahead.
越早布局的人,未来往往越从容。
Those who plan earlier tend to face the future with more ease.

财富认知 010 · Wealth Wisdom 010真正影响生活质量的,是退休后还能留下多少钱点击查看 ▾What matters is how much you get to keep after you retire
分享 →很多人退休后才发现:
Many people only realize after retiring:
真正影响生活质量的,往往不是赚了多少钱,而是退休后还能留下多少钱。
What truly affects quality of life often isn't how much you earned, but how much you get to keep after you retire.
退休规划,不仅是投资,更是税务规划。❤️
Retirement planning isn't just about investing — it's tax planning too. ❤️

财富认知 009 · Wealth Wisdom 009退休,不是拼命存更多钱,而是提前规划点击查看 ▾Retirement isn't about saving desperately — it's about planning ahead
分享 →退休,不是拼命存更多钱,而是提前规划。
Retirement isn't about desperately saving more money — it's about planning ahead.
通过安全、合适的工具,为未来建立持续、稳定、可预期的现金流。
Using safe, suitable tools, build a continuous, stable and predictable cash flow for the future.
越早规划,未来越有选择权,生活越有确定性,也更安心、更从容。
The earlier you plan, the more choices you'll have, the more certainty in life, and the more peace and ease you'll feel.
愿我们都能提前布局未来,让幸福更有保障。
May we all plan ahead for the future, so happiness is better secured.

财富认知 008 · Wealth Wisdom 008金融工具与保障规划,也在不断迭代更新点击查看 ▾Financial tools and protection plans keep evolving too
分享 →任何产品都在不断迭代更新,金融工具与保障规划同样如此。
Every product keeps evolving — and financial tools and protection planning are no exception.
✔ 同样投入,更高保障与价值
✔ 功能更完善,配置更灵活
✔ 方案更贴合当前需求与规划
✔ Same investment, higher protection and value
✔ More complete features, more flexible configuration
✔ Plans better matched to today's needs and goals

财富认知 007 · Wealth Wisdom 007真正的复利思维:建立能持续创造现金流的资产系统点击查看 ▾True compound thinking: build an asset system that generates cash flow
分享 →真正的复利思维,是要建立能够持续创造被动收入与现金流的资产系统。
True compound-interest thinking means building an asset system that can continuously generate passive income and cash flow.
放眼全球,优秀的资产不仅看收益,更要兼顾安全性、流动性与功能性。相比房产等需要长期锁定、变现周期较长的资产,或股票基金等波动较大的投资工具,指数型储蓄人寿保险(IUL)因其灵活性与综合功能,在全球家庭资产配置中持续受到追捧。
Looking globally, a good asset isn't just about returns — it also needs safety, liquidity and functionality. Compared to assets like real estate that require long-term lock-in and have longer liquidation cycles, or more volatile instruments like stocks and funds, Indexed Universal Life insurance (IUL) continues to be sought after in household asset allocation worldwide for its flexibility and combined functionality.
从市场对比来看,在不同地区的表现存在差异,其中美国IUL处于领先位置,且连年全球销量第一。
Comparing markets, performance varies by region, with U.S. IUL in the leading position — it has ranked first in global sales for years running.
它的主要优势在于:
Its main advantages:
是目前全球唯一与美国股票指数挂钩(具备保底机制),且可免费附加较高成本的重疾保障功能的产品。
It is currently the only product worldwide linked to a U.S. stock index (with a downside floor) that can also add a high-value critical illness benefit at no extra cost.
在资金杠杆与运用效率方面表现处于全球领先地位,对比来看约为香港的2倍、台湾的3倍、中国大陆的5倍。
It leads the world in capital leverage and efficiency of use — roughly 2x that of Hong Kong, 3x that of Taiwan, and 5x that of mainland China.
同时,在美国体系当中,它也常被视为唯一的免税型资产。
It is also commonly regarded as the only tax-free asset within the U.S. system.
在功能设计上,它已经超越传统保险的单一保障属性,更是一种多功能金融工具,融合储蓄、现金价值运用、保单贷款、生前保障、身故福利、以及资产隔离、财富传承等综合的智慧规划工具。
In terms of design, it has moved beyond the single protection function of traditional insurance to become a multi-purpose financial tool — combining savings, cash value access, policy loans, living benefits, death benefits, asset protection and wealth transfer into one integrated planning tool.
在不确定性不断增加的时代,无论是通胀压力、退休规划,还是就业结构变化,为自己与家庭建立长期稳定的现金流系统,都变得越来越重要。
In an age of growing uncertainty — whether inflation pressure, retirement planning, or shifts in employment structure — building a long-term, stable cash-flow system for yourself and your family matters more than ever.
越早布局,成本越低;越早规划,未来越从容。
The earlier you plan, the lower the cost; the earlier you prepare, the more at ease your future.

财富认知 006 · Wealth Wisdom 006选择大于努力,健康美丽先行点击查看 ▾Choice matters more than effort — put health and beauty first
分享 →选择大于努力,健康美丽先行;形象一变,市场一片。
Choice matters more than effort — put health and beauty first; change your image, and a whole market opens up.
健康是最好的投资,美丽是最好的名片。从自己开始改变,机会自然会来。
Health is the best investment, beauty is the best business card. Start by changing yourself, and opportunities will follow.

财富认知 005 · Wealth Wisdom 005优先了解并合理配置美国IUL这个多功能金融工具点击查看 ▾Make understanding and setting up a U.S. IUL a priority
分享 →优先了解并合理配置美国IUL,深入学习、理解并善用这一多功能金融工具。
Make it a priority to understand and properly set up a U.S. IUL — study, understand and make good use of this versatile financial tool.
以认知提升财富智慧,以规划守护人生未来,收获从容、安宁、富足与幸福。
Let awareness elevate financial wisdom, let planning safeguard your future, and gain ease, peace, abundance and happiness.

财富认知 004 · Wealth Wisdom 004以前谈婚论嫁看感情,如今要看责任与保障点击查看 ▾In the past, marriage was about love; today, it's also about responsibility
分享 →以前谈婚论嫁看感情,如今要看责任与保障。
In the past, marriage was about love; today, it's also about responsibility and protection.
对于许多未婚男女来说,没有基本的人寿保障和财务规划,总觉得对未来少了一份底气。
For many single men and women, without basic life insurance and financial planning, the future can feel like it's missing a sense of security.

财富认知 003 · Wealth Wisdom 003认知决定选择,选择决定结果;规划决定未来,行动创造财富点击查看 ▾Awareness shapes choice, choice shapes outcome; planning shapes the future, action creates wealth
分享 →美国个人收入与财富结构参考
A Reference on U.S. Personal Income & Wealth Structure
美国个人收入水平(税前)
U.S. Personal Income Levels (Pre-tax)
美国全职工作者中位数约5万~6万美元,高于平均水平约8万~10万美元,15万美元以上属于高收入群体,30万美元以上为少数高收入群体,100万美元以上属于顶尖收入群体。
The median for full-time U.S. workers is about $50,000–$60,000; above-average earners make roughly $80,000–$100,000; $150,000+ is considered high income; $300,000+ places one among a small high-earning group; and $1,000,000+ is top-tier income.
华裔由于教育程度较高、专业岗位比例较多,整体收入通常略高于美国平均水平,较常见在7万~9万美元,专业人士多集中在10万~20万美元以上。
Chinese Americans, with generally higher education levels and a larger share of professional roles, tend to earn somewhat above the U.S. average — commonly $70,000–$90,000, with professionals often in the $100,000–$200,000+ range.
自由职业者收入差异较大,起步阶段约3万~5万美元,稳定经营约5万~10万美元,表现优秀约10万~20万美元,20万美元以上属于高收入群体,50万美元以上通常已具备团队或成熟商业系统。
Self-employed income varies widely: roughly $30,000–$50,000 when starting out, $50,000–$100,000 once established, $100,000–$200,000 for strong performers, $200,000+ is high income, and $500,000+ usually means a team or a mature business system is already in place.
🌱 核心差异
Core Difference
在美国,收入的本质差异不在于工作时间,而在于结构与能力。
打工收入有天花板,自由职业收入看能力,而资产收入决定长期自由度。
In the U.S., the real difference in income isn't about hours worked, but about structure and capability. Employment income has a ceiling, freelance income depends on skill, and asset income determines long-term freedom.
财富自由结构
The Structure of Financial Freedom
财富自由的关键,不只是提高收入,而是建立收入 + 资产 + 现金流的完整系统。
The key to financial freedom isn't just raising income — it's building a complete system of income, assets and cash flow.
在美国,IUL(指数型万能寿险)是普通人可以配置的一种长期、安全、免税的现金流资产工具,可用于税务规划、现金流创造、保障以及资产传承。
In the U.S., IUL (Indexed Universal Life insurance) is a long-term, safe, tax-advantaged cash-flow asset tool available to ordinary people — useful for tax planning, generating cash flow, protection and wealth transfer.
认知决定选择,选择决定结果;规划决定未来,行动创造财富。
Awareness shapes choice, choice shapes outcome; planning shapes the future, action creates wealth.
收入数据来自于 ChatGPT

财富认知 002 · Wealth Wisdom 002不做税务与财富规划,钱只会流向两个地方:税收,或亏损点击查看 ▾Without planning, your money flows to just two places: taxes, or losses
分享 →如果不进行税务与财富规划,钱最终只会流向两个地方:国税局 IRS(税收)或 市场回调(亏损)。市场不会因你努力工作而停止波动,国税局也不会主动为你少收一分税。
Without tax and wealth planning, your money will ultimately flow to just one of two places: the IRS (taxes) or a market pullback (losses). The market won't stop fluctuating just because you work hard, and the IRS won't voluntarily take less from you.

财富认知 001 · Wealth Wisdom 001退休,不是由年龄决定,而是由现金流决定点击查看 ▾Retirement isn't determined by age — it's determined by cash flow
分享 →退休,不是由年龄决定,而是由现金流决定。
Retirement isn't determined by age — it's determined by cash flow.
真正的财务自由,不是拥有多少资产,而是:
持续现金流 ≥ 生活支出。
True financial freedom isn't about how many assets you have — it's: sustained cash flow ≥ living expenses.
当持续的现金流能够覆盖生活成本时,任何时候,都可以选择退休;或者说,任何时候,都可以过上从容、自由的人生。
When your ongoing cash flow can cover your living costs, you can choose to retire at any time — or, put another way, live an easy, free life at any time.
因此,我们一生努力的方向,不只是积累财富,更是建立能够持续创造现金流的资产,让财富持续为自己工作。
So the direction of a lifetime's effort isn't just to accumulate wealth, but to build assets that keep generating cash flow — letting your wealth keep working for you.
财富的终点,不是拥有更多,而是拥有选择生活的自由。
The endpoint of wealth isn't having more — it's having the freedom to choose how you live.

财富成长 Wealth & Growth › 公益财富咨询 Wealth Consultation · 分享此页 →
Wealth Consultation
汇聚具备专业资质的成功人士,提供一对一财富咨询服务,根据您的具体需求量身定制方案,涵盖资产规划、免税规划、儿童教育基金、财富传承、资产增值等方向,助您选择最合适的方案,助力稳健、长期的财富积累。
Bringing together successful professionals with recognized credentials for one-on-one wealth consultation — plans tailored to your needs, covering asset planning, tax-efficient planning, children's education funds, wealth legacy and asset growth, helping you choose the plan that fits you best and supporting stable, long-term wealth growth.

欢迎扫码预约时间,获取专业咨询
Scan to schedule a time for professional consultation
加入我们 · Join Us
微信扫一扫 · WeChat Scan
走进更有质感的生活空间
Step into a life of quality